|
Abstract
We prove the central estimate of the construction: bounds, uniform in the lattice, on the error \(Z\) of the approximate forecast and on the time the forecast spends at large fields. The two halves of the FBSDE give two inequalities which close only together, with small coefficient \(C \lambda^2 / q_{\ast}\), for every coupling and every finite mass. The same bounds hold for the flow restarted from any field at any scale. So the exact flow is an explicit flow with a control of finite relative entropy. This writes the limit measure as an explicit density over an explicit SDE, for the whole lattice sequence, and it gives the FBSDE on the continuum torus, the field equation at every resolution, uniqueness in law for the scalar form of the FBSDE, a renormalised variational formula with no infinite constant, and quartic exponential tails.
The results presented in Lectures 4–7 were obtained recently, with the use of AI, in collaboration with Sarah-Jean Meyer.
Introduction 2
13The energies 4
13.1Moments at fixed cutoff 4
13.2The field equation 4
The forecast equation of Lecture 5 4
The explicit force 5
The smoothed noise 5
13.3Thresholds and energies 6
Exercises 6
14Forward coercivity 6
14.1The scalar model 6
What the scalar lemma says 7
14.2The lattice version 7
14.3A pointwise bound 8
Exercises 9
15Backward feedback and closure 9
15.1The backward representation 9
15.2Three contributions 9
15.3Closing the loop 10
15.4Consequences 11
Exercises 11
Removing the cutoffs 11
16The boundary at infinite resolution 11
16.1The boundary lemma 11
16.2UV stability 12
16.3Restarted laws 12
Exercises 14
17Tightness and tails 14
17.1One Hilbert space 14
17.2Spatial suprema by a maximum principle 14
17.3The terminal field 15
17.4Exponential moments 16
Exercises 17
18Identifying the limit 17
18.1The deterministic coefficients 17
18.2The exact flow as a controlled explicit flow 18
18.3The limit law 20
18.4The filtering model and the FBSDE 22
18.5The renormalised field equation 24
18.6Uniqueness in law and the variational formula 25
18.7What is not proved, and where to go next 27
Summary of the course 28
Exercises 28
References 28
Notation from Lecture 6. We recall the symbols used throughout; the definitions are in Sections 10.1–10.5, 11 and 12 of Lecture 6.
Lattice. \(\Lambda_N\) is the periodic lattice of mesh \(N^{- 1}\) in the unit torus, \(H_N =\mathbb{R}^{\Lambda_N}\), \(\int f = N^{- 3} \sum_x f (x)\), \(\langle u, v \rangle = \int uv\), and \(\| \cdot \|_p\) is the \(L^p\) norm for \(\int\). For a kernel, \(\|C\|_{\text{row}} = \sup_x \int |C (x, z) | \mathrm{d} z\) is the row norm, which bounds \(\|C\|_{p \to p}\) for every \(p\) when \(C\) is symmetric. \(\Delta = \Delta_N\) is the nearest-neighbour Laplacian.
Resolution and free operators (10.1)–(10.2). The resolution \(q \in [q_0, \infty)\) is the squared mass of the regulator, and \(q_0 > 0\) is the squared mass of the Gaussian reference. \(K_q = q - \Delta\) is the precision and \(C_q = K_q^{- 1}\) the covariance of the scales not yet resolved at resolution \(q\); \(\|C_q \|_{p \to p} = q^{- 1}\). In particular \(C = C_{q_0}\) is the covariance of the Gaussian reference and \(K_{q_0} = q_0 - \Delta\) the free field operator. The resolved covariance is \(Q_q = C - C_q\), with \(\partial_q Q_q = C_q^2\), and the bubble \(a_2 (q) = (C_q^2) (x, x) \lesssim q^{- 1 / 2}\) is the variance of the shell at resolution \(q\), by (10.3).
Couplings (11.1). \(\lambda\) is the quartic coupling, \(U (\varphi) = \frac{\lambda}{12} \int \varphi^4\), so that \(D^2 U (y) = \lambda y^2\) and the gradient of the interaction is \(\frac{\lambda}{3} y^3\). \(g_q = \lambda q^{- 1 / 2}\) is the dimensionless coupling and \(r_q = (q / \lambda)^{1 / 2}\) the field size at which the cube balances \(K_q\). \(q_{\ast}\) is the auxiliary scale above which \(g_q\) is small.
Processes (Section 10.3). \(\Phi_q\) is the Polchinski process, with \(\Phi_{q_0} = 0\) and \(\Phi_{\infty} \sim \nu_N\); \(W\) is the Brownian motion on \(H_N\) driving it, \(B\) the Brownian motion of the bridge (10.6), and \(\mathbb{E}_q\) the conditional expectation given the past of \(\Phi\). The forecast is \(\psi_q =\mathbb{E}_q \Phi_{\infty}\), and \(\text{Cov}_q\) is the conditional covariance of \(\Phi_{\infty}\). The filtration is \(\mathcal{F}_q = \sigma (\Phi_s : s \leqslant q)\) (the same letter as the exact force, as in Lecture 6; the meaning is always clear from the context). The forecast is a function of the field, \(\psi_q = m_q (\Phi_q)\), and so is the approximate forecast, \(Y_q = y_q (\Phi_q)\), where \(y = y_q (x)\) solves \(K_q y + \bar{\mathcal{F}}_q (y) = K_q x\).
Forces and coefficients (10.8)–(10.11), (12.5). \(\mathcal{F}_q\) is the exact force in the forecast coordinate, \(K_q \Phi_q = K_q \psi_q +\mathcal{F}_q (\psi_q)\), and \(\bar{\mathcal{F}}_q (y) = \frac{\lambda}{3} y^3 + M_q y + \tilde{\ell}_q (y)\) the explicit approximate force (12.1): the cube, a running mass operator \(M_q = \mu_q I + \Theta_q\) and the clipped corrections \(\tilde{\ell}_q\). \(H_q (y) = (K_q + D \bar{\mathcal{F}}_q (y))^{- 1}\) is the approximate response, \(b_q = - H_q \mathcal{D}_q\) the drift produced by the force defect \(\mathcal{D}_q\), and \(\Xi_q = \text{Cov}_q - H_q (Y_q)\). In the coordinate equation, \(\varrho_q (y) = C_q (M_q y + \tilde{\ell}_q (y))\) collects the linear and the clipped parts of the explicit force.
At the end of Lecture 6 we had, at each lattice cutoff \(N\), the exact system (Theorem 10.6)
where \(Y\) is the approximate forecast built from the explicit force \(\bar{\mathcal{F}}_q\), \(Z = \psi - Y\) is its error, and \(\psi = Y + Z\) is the exact forecast, a martingale. The inputs from Lecture 6, all for \(q \geqslant q_{\ast}\), are:
Global coercivity (Lemma 12.1): \(H_q (y)\) is comparable to \((K_q + \lambda y^2)^{- 1}\) and
\(\varepsilon_q = C (g_q + g_q^2)\).
The source (Proposition 12.2): \(b = b^{\text{b}} + b^{\text{l}}\) with \(\|b^{\text{b}}_q \|_{\infty} \leqslant C \lambda^{7 / 2} q^{- 5 / 2}\) and
where \(t_q (y) = y \mathbb{1}_{|y| > r_q}\).
The coordinate equation (12.5):
with a small Lipschitz correction, \(\|D \varrho_q \|_{p \to p} \leqslant \varepsilon_q\).
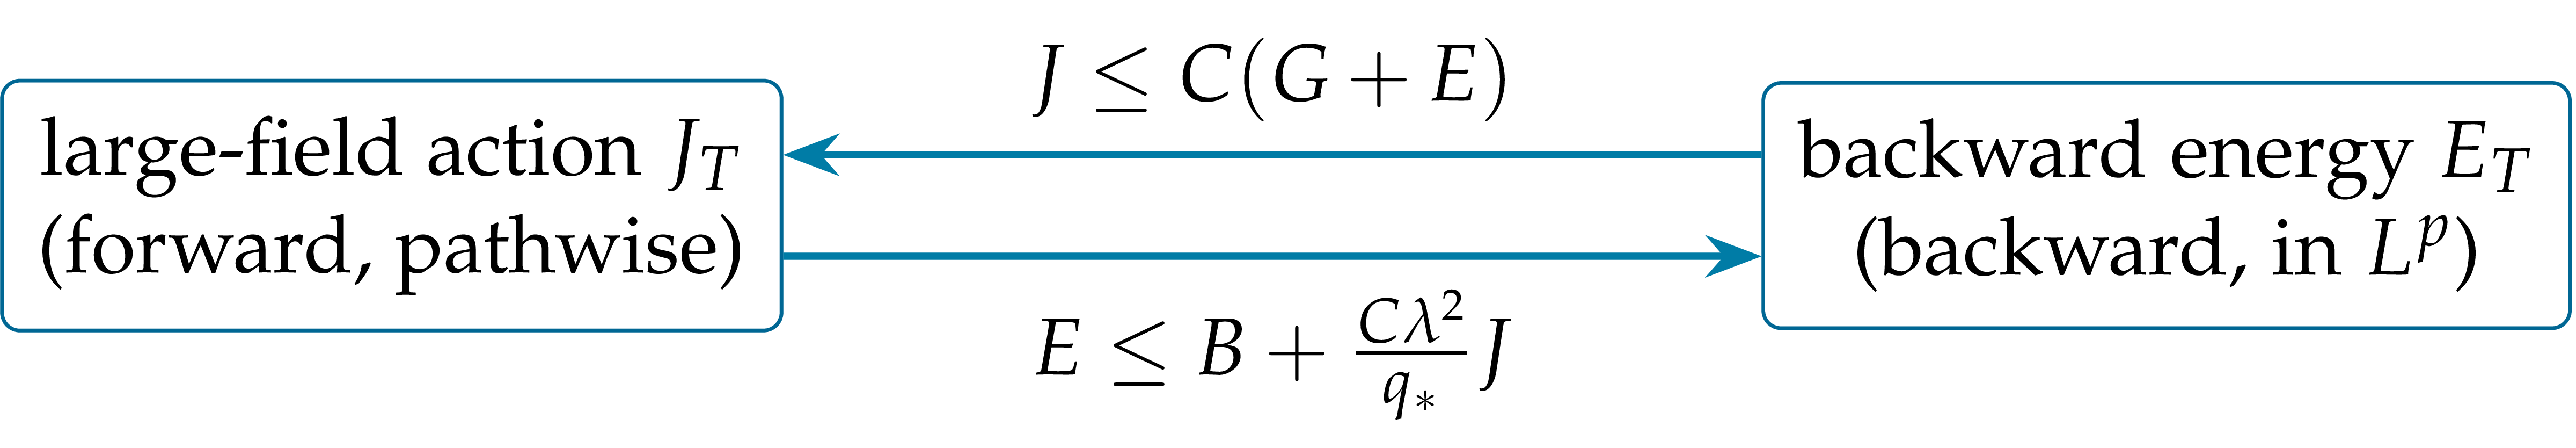
The goal is to show that \(Z\) is small and that \(Y\) rarely visits large fields, uniformly in \(N\). This is UV stability. Neither equation can be estimated alone: the forward equation contains \(Z\), and the source of the backward equation is controlled by the large fields of \(Y\).
How a priori estimates for FBSDEs are usually obtained. For an FBSDE with Lipschitz coefficients one estimates \(\mathbb{E} \|Z_q \|^2\) by Itô's formula and Gronwall, and closes either on a short time interval or under a monotonicity condition [MY99]. Here the time interval is infinite, the coefficients are not uniformly Lipschitz in the relevant norms, and the coupling is not small in a Lipschitz sense. What we have instead is structure: the backward equation is linear in \(Z\), the forward equation is a memoryless cubic elliptic equation at each resolution, and its noise is sub-Gaussian whatever the interaction (Proposition 9.6 of Lecture 5, as far as we know a new observation of these notes).
Where the system starts. The system starts at \(q_0\) with \(Y_{q_0} = Z_{q_0} = 0\). The energies below are integrated from \(q_{\ast}\) (Section 12.5), and no value of \(Y\) at \(q_{\ast}\) is used: this is what the memoryless field equation makes possible. Below \(q_{\ast}\) everything follows from the martingale property of the forecast (Section 16.3).
Sections 13–15 prove these estimates at a fixed lattice and a finite upper scale. Sections 16–18 remove the cutoffs and identify the limit.
The role of the estimates. Each estimate has one job.
Noise bound (Lemma 13.2): the noise \(\zeta\) has free-field tails whatever the interaction. This is where the posterior structure enters.
Forward coercivity (Proposition 14.3): pathwise, at each scale, the cube bounds the large-field part of \(Y\) by the noise tails and \(Z\). It controls where the explicit force is inaccurate.
Backward representation (Lemma 15.1, Proposition 15.2): \(Z\) is the transported defect, as the equation is linear in it. Its energy is bounded by the bounded-field source, a boundary term, and \(C \lambda^2 / q_{\ast}\) times the large-field action. This factor is the only smallness that closes the loop.
Boundary (Lemma 16.1): qualitative, at fixed \(N\). It removes the boundary term, and it is why the upper scale goes first.
UV stability (Theorem 16.2): the result of these four, \(\mathbb{E} \|Z_q \|_2^2 \leqslant Cq^{- 5 / 2}\) uniformly in \(N\). It says that the control turning the explicit flow into the exact one has finite entropy.
Restarted laws (Proposition 16.4): the same from any field at any scale, and below \(q_{\ast}\) by the martingale property of the forecast.
Defect on all fields and Lipschitz coordinate (Lemmas 18.1, 16.3): the defect is integrable along both flows, and the explicit flow is a strong continuum SDE, continuous in the cutoff.
Terminal tail (Section 17): tightness in \(H^{- s}\), \(s > \frac{1}{2}\).
Sources (Proposition 17.3, Theorems 17.4–17.5): quartic tails by a linear source, a restart at \((q_0, hC_{q_0} f)\), and Gaussian tails by a quadratic tilt. These are end results, and nothing else depends on them.
Pointwise bounds (Proposition 14.4, Lemmas 14.5, 17.1): after closure, large fields occur only at finitely many dyadic scales. Neither the loop nor the identification of the limit uses them.
So the formula for \(\nu\) (Theorem 18.5) needs the first five at the start of the flow, and if \(q_0 < q_{\ast}\) the deduction below \(q_{\ast}\) of Proposition 16.4 there, all with first moments of the energies; plus the defect, the coordinate, the tail, the consistency of the coefficients, and moments of the explicit flow, which are Itô's formula. The FBSDE then follows by Girsanov's theorem (Theorem 18.6), with no further estimate on the flow, only the convergence of \(H\) and \(b\) and lower semicontinuity. The restart at every \((q, x)\) gives the kernel \(\Pi_q\): the formula (18.18), the statement that the forecast is a continuous function of the field, its convergence at each scale, and Section 18.6; the sources use it at \((q_0, hC_{q_0} f)\). Higher moments of the energies serve only for the stretched exponential bound, the higher moments in Corollary 17.2 and in Lemma 17.1, and (16.10) with \(p > 1\).
Detailed proofs of what these lectures cite or condense are in the Supplement.
Acknowledgements. The results presented in Lectures 4–7 are joint work with Sarah-Jean Meyer, obtained recently with the use of AI. M. Gubinelli is partly supported by UK Research and Innovation via the grant “StochFields” EP/Z534328/1 and by the Simons Collaboration on Probabilistic Paths to QFT. S.-J. Meyer is supported by the grant “StochFields” EP/Z534328/1.
All estimates below are first proved on a finite interval \([q_{\ast}, T]\) and at fixed \(N\). There, everything is finite.
Lemma
Proof. \(\Phi\) has all maximal moments, since \(\nu_N\) has all moments. Global coercivity, \(K_q + D \bar{\mathcal{F}}_q \geqslant cq\) and \(\bar{\mathcal{F}}_q (0) = 0\), gives \(\|Y_q \| \leqslant C \|K_q \Phi_q \| / q\). Doob's inequality for the martingale \(\psi_q =\mathbb{E}_q \Phi_{\infty}\) gives its maximal moments, and \(Z = \psi - Y\). For the integrands, \(\|\operatorname{Cov}_q \|_{\text{HS}} \leqslant \text{Tr} \operatorname{Cov}_q \leqslant \mathbb{E}_q \| \Phi_{\infty} \|^2\), and \(\|H_q (Y_q)\|_{\text{HS}} \leqslant C \sqrt{\dim H_N} / q\). The energies involve, besides \(Y\) and \(Z\), the field \(\zeta_q\) of Section 13.2 and \(\varrho_q (Y_q)\); finite-dimensional norm equivalence and \(\| \varrho_q (y)\| \leqslant \varepsilon_q \|y\|\) give their moments.\(\Box\)
These constants depend on \(N\) and \(T\). They are used only to justify the absorptions below, never in the final bounds.
| \(\displaystyle \eta_q := K_q \Phi_q - (q - q_0) \psi_q =\mathbb{E}_q [B_{q - q_0}], \) | (13.1) |
the second form by the bridge (10.6),
Since \(F_q = K_q (\psi_q - \Phi_q) = -\mathcal{F}_q (\psi_q)\) and \(K_q = K_{q_0} + q - q_0\), the field equation for the forecast (9.12) of Lecture 5 reads
an elliptic equation for the forecast at resolution \(q\), in which the exact force \(\mathcal{F}_q\) acts with no smoothing operator, and whose noise is controlled whatever the interaction (Proposition 9.6 of Lecture 5, here in one line).
Lemma
| \(\displaystyle \mathbb{E} \mathrm{e}^{u \zeta_q (x)} \leqslant \exp \left( \frac{u^2}{2} (q - q_0) a^2 (q) \right), \qquad (q - q_0) a^2 (q) \leqslant C \sqrt{q}, \) | (13.2) |
uniformly in \(N\).
Proof. Conditional Jensen in
and the forecast by the approximate forecast, \(\psi_q = Y_q + Z_q\).
The coordinate equation \(K_q Y_q + \bar{\mathcal{F}}_q (Y_q) = K_q
\Phi_q\) and
| \(\displaystyle K_{q_0} Y_q + \bar{\mathcal{F}}_q (Y_q) = \eta_q + (q - q_0) Z_q . \) | (13.3) |
This is the forecast equation of Lecture 5 with the explicit force in place of the exact one, and it is the equation we estimate:
it is an elliptic equation at each resolution, with no memory: the past enters only through the noise \(\eta_q\);
the coercivity comes from the cube of \(\bar{\mathcal{F}}_q\), which is explicit;
the price of the replacement is the error \((q - q_0) Z_q\), the only trace of the backward equation, at the same resolution;
the identity is pathwise: no expectation has been taken.
| \(\displaystyle V_q := Y_q + \varrho_q (Y_q) - \zeta_q, \) | (13.4) |
(\(V_q\) is not to be confused with the potentials \(V_t (x)\), \(V_N\)
of Lectures 4–6 and of Sections 16.3 and 18.2; the
potentials are functions of a field, \(V_q\) here is a random field) we
obtain
| \(\displaystyle K_{q_0} V_q + \frac{\lambda}{3} Y_q^3 = (q - q_0) (\zeta_q - \varrho_q (Y_q) + Z_q), \qquad Y_q = V_q + \zeta_q - \varrho_q (Y_q) . \) | (13.5) |
The mass of
Define the signed excess of \(V\) over three quarters of the threshold, the large-field part of \(Y\), and the large values of the noise,
| \(\displaystyle w_q = \text{sgn} (V_q) \left( |V_q | - \tfrac{3}{4} r_q \right)_+, \qquad t_q = Y_q \mathbb{1}_{|Y_q | > r_q}, \qquad \xi_q = \zeta_q \mathbb{1}_{| \zeta_q | > r_q / 32},\) | (13.6) |
all pointwise in space, with \(r_q = (q / \lambda)^{1 / 2}\). The three random energies are
Only thresholded sixth powers are integrated over all scales: \(\mathbb{E} \| \zeta_q \|_6^6\) can be of order \(q^{3 / 2}\), so an unthresholded noise contribution to \(J\) would not be integrable uniformly in \(N\). The weights are matched to each other and to the source bounds:
quantity
weight
reason
\(\|Z_q \|_2^2\)
\(q^{1 / 2}\)
forcing: \(q^{- 3 / 2} \cdot \lambda^{- 1} q^2
\|Z\|_2^2\)
\(\lambda \|t_q \|_6^6\)
\(q^{- 3 / 2}\)
source: \(q^{7 / 2} \|b^{\text{l}} \|^2 \leqslant C
\lambda^3 \cdot \lambda q^{- 3 / 2}
\|t\|_6^6\)
\(\|b^{\text{l}}_q \|_2^2\)
\(q^{7 / 2}\)
backward propagator \(s / q\) and \(\int_q^{\infty}
s^{- 3 / 2} \mathrm{d} s = 2 q^{- 1 / 2}\)
Exercise
Exercise
Exercise
Below the auxiliary scale \(\varrho\) comes from the
frozen force, and is not small. Here the noise is exactly Gaussian,
but the memory has the size of the mass term. Why would testing it
with \(w^3\) need the Hardy inequality \(\|q^{- 1} \int_0^q f\|_{L^4
(q^{- 1 / 2} \mathrm{d} q)} \leqslant \frac{8}{7}
\|f\|_{L^4 (q^{- 1 /
2} \mathrm{d} q)}\), and where would the margin come from? What does
On one site the Laplacian disappears. We also drop the small Lipschitz
correction \(\varrho\) (restored in Proposition 14.3) and
treat the noise and the error as given numbers. Then
Lemma
| \(\displaystyle av + \frac{\lambda}{3} (v + g)^3 = p (g + z) . \) | (14.1) |
Let \(r = (q / \lambda)^{1 / 2}\), \(w =\operatorname{sgn} (v) (|v| - \frac{3}{4} r)_+\), \(\xi = g \mathbb{1}_{|g| > r / 32}\). Then
| \(\displaystyle \frac{q}{8} w^4 + \frac{\lambda}{16} w^6 \leqslant 54 q \xi^4 + \frac{4225}{6} \lambda \xi^6 + \frac{12}{\lambda} q^2 z^2 . \) | (14.2) |
Moreover \(t = (v + g) \mathbb{1}_{|v + g| > r}\) satisfies \(|t| \leqslant \frac{32}{7} (|w| + | \xi |)\).
Proof. Multiply
This is the large-field coercivity: above the threshold the cube
provides a sixth power, a quartic term of the size of a mass \(q\), and
a cubic term which dominates the noise below the threshold. On the right
side, \(pgw^3 \leqslant \frac{qr}{32} |w|^3 + q | \xi | |w|^3\), and the
first term is absorbed. By Young's inequality, \(q | \xi | |w|^3
\leqslant \frac{q}{8} w^4 + 54 q \xi^4\) and \(q |z| |w|^3 \leqslant
\frac{\lambda}{48} w^6 + \frac{12}{\lambda} q^2 z^2\). This gives
Lemma
Proof. \(\frac{1}{4} x^3 + 64 \rho^3 - 3 x^2 \rho = \frac{1}{4} (x - 8 \rho)^2 (x + 4 \rho) \geqslant 0\), so \((x - \rho)^3 \geqslant x^3 - 3 x^2 \rho - \rho^3 \geqslant \frac{3}{4} x^3 - 65 \rho^3\). Apply it with \(x = u + b\), \(b = \frac{11}{16} r\): \(\frac{1}{3} u^3 (x - \rho)^3 \geqslant \frac{1}{4} u^3 x^3 - \frac{65}{3} u^3 \rho^3\), and \(x^3 \geqslant u^3 + 3 b^2 u + b^3\) with \(\frac{3}{4} b^2 = \frac{363}{1024} r^2 > \frac{1}{4} r^2\) and \(\frac{1}{4} b^3 = \frac{1331}{16384} r^3 > \frac{1}{13} r^3\). Finally \(\frac{65}{3} u^3 \rho^3 \leqslant \frac{1}{6} u^6 + \frac{4225}{6} \rho^6\), and \(\frac{1}{4} - \frac{1}{6} = \frac{1}{12}\).\(\Box\)
Proposition
| \(\displaystyle q \|w_q \|_4^4 + \lambda \|w_q \|_6^6 + \lambda \|t_q \|_6^6 \leqslant C (q\| \xi_q \|_4^4 + \lambda \| \xi_q \|_6^6 + \lambda^{- 1} q^2 \|Z_q \|_2^2) . \) | (14.4) |
Consequently, for every \(T\),
| \(\displaystyle J_T \leqslant C (G_T + E_T), \qquad \|G_T \|_{L^p (\mathbb{P})} \leqslant C \lambda^3 p^5 \quad (p \geqslant 1), \) | (14.5) |
with \(C\) independent of \(N\), \(T\) and \(p\).
Proof: the changes from the scalar case. Test
The elliptic term. \(\langle w^3, K_{q_0} V \rangle \geqslant 0\). Indeed \(w^3 = \phi' (V)\) for the convex function \(\phi (v) = \frac{1}{4} (|v| - \frac{3}{4} r)_+^4\), \(Vw^3 \geqslant 0\), and for any nondecreasing \(\phi'\),
summing over unordered nearest-neighbour pairs. So the elliptic term only helps.
The coordinate correction. Split \(\varrho_q (y) = \varrho_q^0 + \varrho_q^1\) according to \(|y| \leqslant r_q\) or not (writing \(\varrho_q (y) = L_q (y) y\) with \(L\) the averaged derivative). Then \(\| \varrho_q^0 \|_{\infty} \leqslant \varepsilon_q r_q \leqslant r_q / 32\) shifts the threshold, and \(\| \varrho_q^1 \|_j \leqslant \varepsilon_q \|t_q \|_j\), \(j = 4, 6\). Then \(|Y| \leqslant |w| + \frac{13}{16} r_q + | \xi | + | \varrho^1 |\); on \(\{|Y| > r_q \}\) this gives \(\frac{3}{16} |Y| \leqslant |w| + | \xi | + | \varrho^1 |\), so for small \(\varepsilon\)
This also supplies the \(t\) part of
The error. \(| \langle w^3, (q - q_0) Z \rangle | \leqslant
\frac{\lambda}{48} \|w\|_6^6 +
\frac{12}{\lambda} q^2 \|Z\|_2^2\).
Multiplying
Tails of the noise. By Minkowski's inequality in \(x\), for \(j
= 4, 6\), \(\|\| \xi_q \|_j^j \|_{L^p (\mathbb{P})} \leqslant \sup_x \||
\xi_q (x) |^j
\|_{L^p (\mathbb{P})}\), and by Hölder and
and integrating in \(q\) with \(u = \sqrt{q} / (p \lambda)\) gives \(\|G_T \|_p \leqslant C \lambda^3 p^5\).\(\Box\)
No information on the interacting field has been used, apart from the equation itself and the posterior structure of the noise. The tails of \(\zeta\) are those of the free field whatever the interaction: this replaces the subtraction of a Gaussian field.
The maximum principle gives more than the integrated estimate: a bound in \(L^{\infty}\) driven by the cube alone.
Proposition
| \(\displaystyle \|Y_q \|_{\infty} \leqslant C \left[ \left( \frac{q}{\lambda} \right)^{1 / 3} \| \zeta_q \|_{\infty}^{1 / 3} +\| \zeta_q \|_{\infty} + q^{1 / 4} + q\|Z_q \|_2 \right] . \) | (14.6) |
In particular there is \(c > 0\) such that \(t_q = 0\), i.e. \(\|Y_q \|_{\infty} \leqslant r_q\), whenever \(\| \zeta_q \|_{\infty} + q \|Z_q \|_2 \leqslant cr_q\): large fields occur only when the noise or the error is large.
Proof. Let \(p = q - q_0\), \(d = \zeta_q -
\varrho_q (Y_q)\), and remove the error by \(\mathcal{H}= pC_{q_0}
Z_q\). Then \(\|\mathcal{H}\|_{\infty} \leqslant pa_2 (q_0)^{1 / 2}
\|Z_q \|_2 \leqslant Cq
\|Z_q \|_2\), since the kernel of \(C_{q_0}\) is
in \(L^2\) uniformly in \(N\) by (10.3). By
At a positive maximum of \(W\), \(K_{q_0} W \geqslant 0\), so \(W + D
\leqslant (3 p\|d\|_{\infty} / \lambda)^{1 / 3}\) there; similarly at a
negative minimum. Hence \(\|Y_q \|_{\infty} \leqslant 2 \|D\|_{\infty} +
(3 q\|d\|_{\infty} /
\lambda)^{1 / 3}\). With \(\| \varrho_q
(Y_q)\|_{\infty} \leqslant \varepsilon_q \|Y_q \|_{\infty}\), the term
\(2 \varepsilon_q \|Y_q \|_{\infty}\) is absorbed, and by Young's
inequality \((q \varepsilon_q \|Y_q \|_{\infty} / \lambda)^{1 / 3}
\leqslant \frac{1}{4}
\|Y_q \|_{\infty} + C (q \varepsilon_q /
\lambda)^{1 / 2}\), where \(q \varepsilon_q / \lambda \leqslant C
\sqrt{q}\) since \(g_q = \lambda q^{- 1 / 2}\). This proves
Lemma
Proof. At fixed \(q\) the norm \(f \mapsto \|C_q f\|_{\infty}\) is convex, so by Lemma 13.2 \(\| \zeta_q \|_{\infty}\) is dominated by the supremum of the Gaussian field \(C_q B_{q - q_0}\). Its variance is at most \(C \sqrt{q}\), and for \(\theta < 1\) its increments have variance at most \(C \sqrt{q} (\sqrt{q} |x - y|)^{\theta}\) uniformly in \(N\), so Dudley's bound gives the mean \(\lesssim q^{1 / 4} \sqrt{\log (2 + q)}\) and Gaussian concentration gives fluctuations at the scale \(q^{1 / 4}\). For the supremum over \(s \in [Q, 2 Q]\), write \(C_s = C_{2 Q} K_{2 Q} C_s\), where \(\|K_{2 Q} C_s \|_{\infty \to \infty} \leqslant 2\). Since \(\mathrm{d} \eta_q = (I - (q - q_0) \text{Cov}_q) \hspace{0.17em} \mathrm{d} W_q\) by (10.5) and (10.7), \(\eta\) is a martingale, \(\|C_{2 Q} \eta_s \|_{\infty}\) is a submartingale, and Doob's inequality gives, for \(p \geqslant 2\), \(\| \sup_{s \in [Q, 2 Q]} \| \zeta_s \|_{\infty} \|_{L^p} \leqslant CQ^{1 / 4} (\sqrt{\log (2 + Q)} + \sqrt{p})\). Markov's inequality with \(p \asymp \vartheta^2 \log (2 + Q)\) bounds the probability that the normalised supremum over \([Q, 2 Q]\) exceeds \(\vartheta\) by \((2 + Q)^{- c \vartheta^2}\), for \(\vartheta \geqslant \vartheta_0\). This is summable over dyadic \(Q\), and \(\|\mathcal{N}\|_p \leqslant C \sqrt{p}\) follows.\(\Box\)
Exercise
Exercise
Exercise
The backward equation in
| \(\displaystyle \partial_s \mathcal{P}_{q, s} =\mathcal{P}_{q, s} H_s (Y_s), \qquad \mathcal{P}_{q, q} = I, \qquad s \geqslant q.\) | (15.1) |
By (A), \(\|\mathcal{P}_{q, s} \|_{2 \to 2} \leqslant \exp \int_q^s \frac{1 + \varepsilon_u}{u} \mathrm{d} u \leqslant L_0 \hspace{0.17em} \frac{s}{q}\), with \(L_0 = \exp (\int_{q_{\ast}}^{\infty} \varepsilon_u \frac{\mathrm{d} u}{u}) \leqslant \exp (C (g_{q_{\ast}} + g_{q_{\ast}}^2))\).
Proof. By the product rule and
So \(Z\) is the expected source accumulated on the unresolved scales, transported back to \(q\), plus the boundary error. This is the conditional-expectation form of a backward equation, as in \(F_t =\mathbb{E}_t [F_T]\) for the force (Theorem 7.3 of Lecture 4); here the source is the defect.
Split \(Z = Z^{\text{t}} + Z^{\text{b}} + Z^{\text{l}}\) according to the terminal term and the two parts of the source. We estimate each in the scalar manner: norms of the propagator times norms of the source.
Bounded fields. By (B),
This is where the two correction steps of Lecture 6 are used: with one step the source would be \(O (s^{- 2})\) and the first integral would diverge logarithmically.
Boundary. \(q \|Z^{\text{t}}_q \|_2 \leqslant L_0 \hspace{0.17em} \mathbb{E}_q \|TZ_T \|_2\), so, with \(\delta_{N, T, p} := \|TZ_T \|^2_{L^{2 p} (\mathbb{P}; L^2)}\),
At fixed \(N\), \(\delta_{N, T, p} \to 0\) as \(T \to \infty\) (Lemma 16.1).
Large fields. Let \(A^{\text{l}} := \int_{q_{\ast}}^T s^{7 / 2} \|b^{\text{l}}_s (Y_s)\|_2^2 \mathrm{d} s \leqslant C \lambda^4 \int s^{- 3 / 2} \|t_s \|_6^6 \leqslant C \lambda^3 J_T\) by (B). By Cauchy–Schwarz in \(s\),
so that, by Jensen's inequality, \(\|Z^{\text{l}}_q \|_2^2 \leqslant 2 L_0^2 q^{- 5 / 2} \hspace{0.17em} \mathbb{E}_q A^{\text{l}}\). Integrating, and using that \(\mathbb{E}_q\) is a contraction on \(L^p (\mathbb{P})\),
Proposition
| \(\displaystyle \|E_T \|_{L^p} \leqslant C \lambda^6 q_{\ast}^{- 3 / 2} + C \lambda^{- 1} q_{\ast}^{- 1 / 2} \hspace{0.17em} \delta_{N, T, p} + C \lambda^2 q_{\ast}^{- 1} \|J_T \|_{L^p},\) | (15.3) |
with \(C\) independent of \(N\), \(T\) and \(p\).
Proof. \(\|Z\|^2 \leqslant 3 (\|Z^{\text{t}} \|^2 +\|Z^{\text{b}} \|^2 +\|Z^{\text{l}} \|^2)\) and the three estimates above.\(\Box\)
Proof. Let \(x = \|E_T \|_p\) and \(y = \|J_T \|_p\). By Propositions 14.3 and 15.2,
with \(A_0, B_0, B_1\) and the constant in \(\theta\) independent of \(N, T, p\), and bounded for all \(q_{\ast}\) beyond the thresholds already required. Choose \(q_{\ast}\) such that also \(A_0 \theta \leqslant \frac{1}{2}\). Then \(y \leqslant A_0 (C \lambda^3 p^5 + B_0 + B_1 \delta_{N, T, p}) + \frac{1}{2} y\). Since \(y < \infty\) by Lemma 13.1, it can be absorbed, and \(x\) follows.\(\Box\)
The structure of the argument is the point:
The smallness is in the feedback, \(\lambda^2 / q_{\ast}\), not in the coupling of either equation, and it is independent of the moment order, so a single \(q_{\ast}\) closes the loop for every \(p\). The growth \(p^5\) is then inherited from the tails of the noise, \(G_T\), and gives stretched exponential moments \(\mathbb{E} \exp \{c (E_{\infty} + J_{\infty})^{1 / 5} \} < \infty\) once the boundary term is removed. Note that \(\lambda^2 / q_{\ast} = g_{q_{\ast}}^2\).
The boundary term \(\delta_{N, T, p}\) is removed in Section 16, at each fixed \(N\), by letting \(T \to \infty\). Assuming this for the moment, we obtain
| \(\displaystyle \sup_N \|E^N_{\infty} \|_{L^p} + \sup_N \|J^N_{\infty} \|_{L^p} \leqslant C_{\lambda} (1 + p^5), \qquad \sup_N \mathbb{E} \|Z^N_q \|_2^2 \leqslant C_{\lambda} q^{- 5 / 2} .\) | (15.5) |
The second bound follows from the representation formula on \([q, \infty)\): the three contributions are, up to the factor \(3\), \(O (q^{- 3})\), \(0\) and, by the computation above, \(2 L_0^2 q^{- 5 / 2} \mathbb{E}A^{\text{l}}\). So the approximate forecast differs from the exact one by \(O (q^{- 5 / 4})\) in \(L^2 (\mathbb{P}; L^2)\) (root mean square), uniformly in the lattice. Since \(\|H_q \| \leqslant C / q\), the coupling term \(H_q Z_q\) in the forward equation is \(O (q^{- 9 / 4})\) in \(L^2 (\mathbb{P}; L^2)\), integrable in \(q\): the forward equation is, up to an integrable drift, the explicit SDE \(\mathrm{d} Y = b (Y) \mathrm{d} q + H (Y) \mathrm{d} W\). The same computation holds along the path. At \(T = \infty\) the boundary part vanishes (Lemma 16.1) and, with \(A^{\text{l}}\) now integrated up to \(\infty\) (it has all moments, since \(A^{\text{l}} \leqslant C \lambda^3 J_{\infty}\)), \(q^{5 / 2} \|Z_q \|_2^2 \leqslant 3 (C \lambda^7 q_{\ast}^{- 1 / 2} + 2 L_0^2 \mathbb{E}_q A^{\text{l}})\). Since \(\mathbb{E}_q A^{\text{l}}\) is a martingale, Doob's inequality gives, for \(p \geqslant 2\),
| \(\displaystyle \| \sup_{q \geqslant q_{\ast}} q^{5 / 2} \|Z_q \|_2^2 \|_{L^p (\mathbb{P})} \leqslant C_{\lambda} (1 + p^5) . \) | (15.6) |
Exercise
In which sense do large fields make the backward equation more contractive? Redo the three estimates of Section 15 on one site.
Exercise
Exercise
Sections 13–15 proved (15.4) at every lattice cutoff \(N\) and every upper scale \(T\). Three things remain.
Show that the boundary term vanishes: \(TZ_T \to 0\) as \(T \to \infty\) at fixed \(N\) (Section 16).
Turn the uniform energy bounds into tightness of the measures (Section 17).
Identify the limit: the deterministic coefficients; then, from the restarted flow, the limit as an explicit density over an explicit flow, along the whole sequence; then the equations, read off by Girsanov's theorem (Section 18).
At a fixed lattice, the terminal resolution is \(q = \infty\), and the field at resolution \(q\), \(\Phi_q\), converges to the terminal field \(\Phi_{\infty}\). The approximate force \(\bar{\mathcal{F}}_q\) was built to converge to the bare force: \(\mu_q \to \mu_N\), \(\Theta_q \to 0\), and the nonlinear corrections were integrated from \(q = \infty\), so that they vanish there. This is the boundary condition of the backward equation.
Lemma
The constants depend on \(N\); this is not a uniform estimate.
Proof. All norms on \(H_N\) are equivalent, and we do not track the dependence on \(N\).
The field at resolution \(q\). By (10.6), \(\Phi_q = (q - q_0) C_q \Phi_{\infty} + C_q B_{q - q_0}\), and \((q - q_0) C_q - I = - C_q K_{q_0} = O (q^{- 1})\), \(\|C_q B_{q - q_0} \|_{L^p} = O (q^{- 1 / 2})\). So \(\| \Phi_q - \Phi_{\infty} \|_{L^p} \leqslant C_{N, p} q^{- 1 / 2}\).
The approximate forecast. Global coercivity gives \(\|Y_q \| \leqslant C \|K_q \Phi_q \| / q\), bounded in every \(L^p\) uniformly in \(q\). The coordinate equation \(\Phi_q = Y_q + C_q \bar{\mathcal{F}}_q (Y_q)\) and the bounds \(| \mu_q | \leqslant C_N\), \(\| \Theta_q \|_{\text{row}} = O_N (q^{- 1 / 2})\) and \(\| \tilde{\ell}_q (y)\|_{\infty} \leqslant C \textsf{S}_4 (\ell^{[2]}_q) \|y\|_{\infty}^3 \leqslant C \lambda^2 q^{- 1 / 2} \|y\|_{\infty}^3\) (Taylor from the four-leg vertex, since the low jet vanishes) show that \(\bar{\mathcal{F}}_q (Y_q)\) is bounded in \(L^p\), so \(\|Y_q - \Phi_q \|_{L^p} = O (q^{- 1})\). Moreover \(| \mu_q - \mu_N | = O_N (q^{- 1})\), and therefore
| \(\displaystyle \| \bar{\mathcal{F}}_q (Y_q) - DV_N (\Phi_{\infty})\|_{L^p} \leqslant C_{N, p} q^{- 1 / 2} .\) | (16.2) |
Thus the explicit force at the approximate forecast converges to the bare force at the terminal field.
The error. Subtract the approximate coordinate equation \(K_q \Phi_q = K_q Y_q + \bar{\mathcal{F}}_q (Y_q)\) from the exact one ((10.5) and Proposition 10.4(b)), \(K_q \Phi_q = K_q \psi_q +\mathbb{E}_q [DV_N (\Phi_{\infty})]\):
| \(\displaystyle qZ_q = qC_q [\bar{\mathcal{F}}_q (Y_q) -\mathbb{E}_q DV_N (\Phi_{\infty})] .\) | (16.3) |
Let \(G = DV_N (\Phi_{\infty})\) and \(G^0_q = DV_N (\Phi_q)\), which is
\(\mathcal{F}_q\)-measurable. Then \(\|\mathbb{E}_q G - G\|_{L^p}
\leqslant \|\mathbb{E}_q (G - G^0_q)\|_{L^p} +
\|G^0_q - G\|_{L^p}
\leqslant 2 \|G - G^0_q \|_{L^p} = O (q^{- 1 / 2})\), by the cubic
Lipschitz bound for \(DV_N\) and the first step. With
The proof uses no estimate uniform in \(N\), and no concentration of the posterior: only that the Polchinski process \(\Phi_q\), which is \(\mathcal{F}_q\)-measurable, converges to the hidden field. In Lecture 4 language, the forecast and the field at resolution \(q\) have the same limit at infinite resolution, and the force \(F_q = K_q (\psi_q - \Phi_q)\) converges to the bare force \(- DV_N (\Phi_{\infty})\) (Exercise 16.1; recall \(F_q =\mathbb{E}_q [- DV_N (\Phi_{\infty})]\) by (10.5), so this is the conditional-expectation step of the proof).
Now let \(T \to \infty\) at fixed \(N\) in
Theorem
| \(\displaystyle \sup_N (\|E^N_{\infty} \|_{L^p} +\|J^N_{\infty} \|_{L^p}) \leqslant C_{\lambda} (1 + p^5), \qquad \sup_N \mathbb{E} \|Z^N_q \|_2^2 \leqslant C_{\lambda} q^{- 5 / 2},\) | (16.4) |
and
for small \(c > 0\).
Proof. Monotone convergence in
The coordinate is Lipschitz for the uniform norm, by the maximum principle.
Lemma
Proof. With \(\delta = y - y'\), \(h = x - x'\), \(a = \delta + \varrho_s (y) - \varrho_s (y')\), (12.5) gives \(K_s (a - h) + \frac{\lambda}{3} (y^3 - (y')^3) = 0\). At a positive maximum of \(a - h\), \(K_s (a - h) \geqslant s (a - h) > 0\), so \(y^3 < (y')^3\) there, i.e. \(\delta < 0\) and \(a - h \leqslant \| \varrho_s (y) - \varrho_s (y')\|_{\infty} + \|h\|_{\infty}\); similarly at a negative minimum. Since \(\varrho_s\) is \(\varepsilon_s\)-Lipschitz on \(L^{\infty}\), \(\| \delta \|_{\infty} \leqslant 2 \|h\|_{\infty} + 2 \varepsilon_s \| \delta \|_{\infty}\). For \(s < q_{\ast}\) use (12.18) and \(\|C_{q_{\ast}} K_s \|_{\infty \to \infty} \leqslant 2\). Finally \(\|C_s \|_{\infty \to \infty} = 1 / s\).\(\Box\)
The estimates above use the start of the flow only through the noise. So they hold, with the changes below, for the flow restarted from any field at any scale, and these estimates are the input of Section 18.2. Let \(\mathrm{e}^{- V_q (x)} =\mathbb{E} \mathrm{e}^{- V_N \left( x + \int_q^{\infty} C_s \hspace{0.17em} \mathrm{d} W_s \right)}\), and define the exact force \(F_q = - DV_q\), and let \(\mathbb{P}^{q, x}\) be the exact flow conditioned on \(\Phi_q = x\), \(\hspace{0.17em} \mathrm{d} \Phi = - C_s^2 DV_s (\Phi) \hspace{0.17em} \mathrm{d} s + C_s \hspace{0.17em} \mathrm{d} W\). Fix \(N\), \(q \geqslant q_0\) and \(x \in H_N\), \(R = \|x\|_{\infty}\). By the Markov property of the flow, \(\mathbb{P}^{q, x}\) is the law of \(\Phi_t = C_t (K_q x + (t - q) \hat{\Phi} + B'_{t - q})\), \(t \geqslant q\), where \(B'\) is a Brownian motion independent of \(\hat{\Phi}\), and \(\hat{\Phi}\) has the law
Note that \(\nu^{[q_0, 0]} = \nu_N\), so \(\mathbb{P}^{q_0, 0}\) is the flow itself. The posterior given \(\Phi_t\) is \(\propto \exp \left( \langle z, K_t \Phi_t \rangle - \frac{1}{2} \langle z, K_t z \rangle - V_N (z) \right) \hspace{0.17em} \mathrm{d} z\), the same function of \(\Phi_t\) as for \(\nu_N\). So \(\psi_t = m_t (\Phi_t)\), and \(Y_t\), \(Z_t = \psi_t - Y_t\) and the system (1) are unchanged, with the same coefficients and with \(Y_q = y_q (x)\), \(\|Y_q \|_{\infty} \leqslant 6 R\) by Lemma 16.3. Let \(\eta_t = K_t \Phi_t - (t - q) \psi_t = K_q x +\mathbb{E}_t B'_{t - q}\), \(\zeta_t = C_t \eta_t\). Then
| \(\displaystyle \zeta_t = d_t + \zeta^0_t, \quad d_t = C_t K_q x, \quad \zeta^0_t = C_t \mathbb{E}_t B'_{t - q} . \) | (16.6) |
Here \(C_t K_q = I - (t - q) C_t\) and \((t - q) C_t\) has a positive kernel of total mass at most \(1\), so \(\|d_t \|_{\infty} \leqslant 2 R\). By conditional Jensen, \(\zeta^0\) satisfies Lemma 13.2, with \((t - q) a_2 (t) \leqslant C \sqrt{t}\). With the field \(V_t = Y_t + \varrho_t (Y_t) - \zeta_t\) of (13.4) (not the potential \(V_t (x)\), always written with its argument), the computation of (13.5) with \(q_0\) replaced by \(q\) gives the field equation
| \(\displaystyle K_q V_t + \frac{\lambda}{3} Y_t^3 = (t - q) (\zeta_t - \varrho_t (Y_t) + Z_t) . \) | (16.7) |
It has the form of (13.5), with mass \(K_q \geqslant 0\) and \(0 \leqslant t - q \leqslant t\), and it holds for \(t \geqslant q_{\ast}\) also when \(q < q_{\ast}\), as it uses only \(K_t = K_q + t - q\) and the coordinate equation at \(t\).
Proposition
| \(\displaystyle \|E_{\infty} \|_{L^p (\mathbb{P}^{q, x})} + \|J_{\infty} \|_{L^p (\mathbb{P}^{q, x})} \leqslant C (1 + p^5 + p^3 R^6), \) | (16.8) |
| \(\displaystyle \mathbb{E}^{q, x} \|Z_s \|_2^2 \leqslant C (1 + R^6) s^{- 5 / 2}, \quad \mathbb{E}^{q, x} \|Y_s \|_2^2 \leqslant C (1 + R^6) (R^2 + s^{1 / 2}), \quad s \geqslant q^{\vee} . \) | (16.9) |
Below the auxiliary scale, if \(q < q_{\ast}\), for \(p \geqslant 1\),
Proof. Forward. Proposition 14.3 applies pathwise to (16.7): its proof uses only a nonnegative mass, a right-side coefficient \(t - q \in [0, t]\), the positivity of \(\langle w^3, K_q V \rangle\) and the bounds on \(\varrho\). So \(J_T \leqslant C (G_T + E_T)\) with \(G_T\) built on \(\xi_t = \zeta_t 1_{| \zeta_t | > r_t / 32}\).
The noise. Let \(q_R = (128)^2 \lambda R^2\), so that \(2 R \leqslant r_t / 64\) for \(t \geqslant q_R\). For such \(t\), \(| \zeta | > r_t / 32\) forces \(| \zeta^0 | > r_t / 64\) and \(| \zeta | \leqslant 2 | \zeta^0 |\), and the proof of (14.5) applies to \(\zeta^0\) with this threshold. For \(q \leqslant t < q_R\) use \(\| \xi_t \|_j^j \leqslant C (R^j +\| \zeta^0_t \|_j^j)\) and \(\|\| \zeta^0_t \|_j^j \|_{L^p} \leqslant Cp^{j / 2} t^{j / 4}\). Then the part of \(G\) on \([q^{\vee}, q_R)\) has \(L^p\) norm at most
the constant depending on \(\lambda\). So \(\|G_T \|_p \leqslant C (p^5 + p^3 R^6)\).
Backward and closure. Lemma 13.1 holds as \(\nu^{[q, x]}\) has all moments. Lemma 15.1 and Proposition 15.2 hold on \([q^{\vee}, T]\), as they use only the propagator (15.1), the deterministic bounds (B) on \(b^{\text{b}}, b^{\text{l}}\) and the conditional expectations; the feedback coefficient is \(C \lambda^2 / q^{\vee} \leqslant C \lambda^2 / q_{\ast}\). No initial value of \(Y\) at \(q^{\vee}\) is used. So Theorem 15.3 holds with \(\delta_{T, p}\) computed under \(\mathbb{P}^{q, x}\). Boundary: the proof of Lemma 16.1 applies at fixed \(N\), with \(\Phi_t \to \hat{\Phi}\) and the coordinate equation \(K_t \Phi_t = K_t \psi_t +\mathbb{E}_t DV_N (\hat{\Phi})\), so \(\delta_{T, p} \to 0\). This proves (16.8). The bound on \(Z\) follows from the representation (15.2) as in (15.5). The bound on \(Y\) follows from Itô's formula for \(\|Y\|_2^2\) in the system (1), with \(\|Y_q \|_2 \leqslant 3 R\) if \(q \geqslant q_{\ast}\) and the moments of \(Y_{q_{\ast}}\) below if \(q < q_{\ast}\), the linear bound on \(b\), \(\|H\| \leqslant C / s\) and \(\text{Tr} H^2 \leqslant Cs^{- 1 / 2}\).
Below the auxiliary scale: the deduction. Let \(q < q_{\ast}\). By the representation (15.2) at \(q_{\ast}\) and conditional Jensen, \(\|Z_{q_{\ast}} \|_2\) has all moments. By (14.4) at \(t = q_{\ast}\), pathwise, \(\lambda \|t_{q_{\ast}} \|_6^6 \leqslant C (q_{\ast} \| \xi \|_4^4 + \lambda \| \xi \|_6^6 + \lambda^{- 1} q_{\ast}^2 \|Z_{q_{\ast}} \|_2^2)\), and \(\|Y_{q_{\ast}} \|_2 \leqslant r_{q_{\ast}} + \|t_{q_{\ast}} \|_6\). So \(\psi_{q_{\ast}} = Y_{q_{\ast}} + Z_{q_{\ast}}\) has all moments in \(L^2\). As \(\psi\) is a martingale, \(\mathbb{E} \| \psi_s \|_2^{2 p} \leqslant \mathbb{E} \| \psi_{q_{\ast}} \|_2^{2 p}\) for \(s \leqslant q_{\ast}\), by Jensen. Now \(Y_s = y_{q_{\ast}} (x'_s)\) with \(x'_s = C_{q_{\ast}} K_s \Phi_s = C_{q_{\ast}} K_q x + (s - q) C_{q_{\ast}} \psi_s + C_{q_{\ast}} \mathbb{E}_s B'_{s - q}\). By Lemma 16.3, \(\|Y_s \|_{\infty} \leqslant 3 \|x'_s \|_{\infty}\), as \(y_{q_{\ast}} (0) = 0\), and \(C_{q_{\ast}} : L^2 \to L^{\infty}\) is bounded uniformly in \(N\), while \(\|C_{q_{\ast}} \mathbb{E}_s B'_{s - q} \|_{\infty}\) is dominated in every convex moment by the supremum of a Gaussian field at the fixed scale \(q_{\ast}\), by conditional Jensen as in Lemma 13.2. This bounds \(\mathbb{E} \|Y_s \|_{\infty}^{2 p}\). Then \(Z_s = \psi_s - Y_s\). This proves (16.10).\(\Box\)
Exercise
Exercise
To compare lattices, partition \(\mathbb{T}^3\) into cubic cells \(\square_x\) of side \(N^{- 1}\) centred at \(x \in \Lambda_N\), and let
\(\iota_N : H_N \to H = L^2 (\mathbb{T}^3)\) is an isometry, \(j_N = \iota_N^{\ast}\), and \(\textsf{P}_N \to I\) strongly. Fields are embedded by \(\iota_N\), operators by \(\iota_N \cdot j_N\). The embedded innovation has covariance \(\textsf{P}_N\); in the limit it becomes a cylindrical Brownian motion on \(H\), obtained as the limit of the lattice innovations.
The energy bounds control \(L^4\) and \(L^6\) norms of large fields. Spatial suprema at finite resolution come from the \(L^{\infty}\) coercivity of Proposition 14.4.
Lemma
uniformly in \(N\).
Proof. By the definitions, \(\| \zeta_q
\|_{\infty} \leqslant q^{1 / 4} (\log (2 + q))^{1 / 2} \mathcal{N}\)
and \(q \|Z_q \|_2 \leqslant q^{- 1 / 4} \mathcal{Z}\). Inserting these
in
Any exponent below \(\frac{1}{2}\) keeps \(Y\) below the threshold \(r_q\) at large \(q\). The exponent \(5 / 12\) comes from the cube alone. The memory form of Exercise 13.3, with a weight in \(q\) absorbing the memory, gives every exponent above \(\frac{1}{4}\), at the price of that absorption.
At the terminal resolution there is no such bound: \(\Phi_{\infty}\) is a distribution.
What the pointwise bound gives, and what it does not. The \(L^{\infty}\) bound cannot replace Proposition 14.3 in the loop: it is linear in \(q \|Z_q \|_2\), so its sixth power is not controlled by the energy \(E\), while the test with \(w^3\) gives a bound quadratic in \(Z\). Once the loop has closed it does give more. Almost surely \(\|Y_q \|_{\infty} \ll r_q\) past a random scale, so large fields occur only at finitely many dyadic scales, and \(\mathcal{D}_q (Y_q)\) is then the bounded-field defect alone. Suprema over finite intervals of scales \(\geqslant q_{\ast}\) have all moments uniformly in \(N\), which is the boundedness part of the hypothesis of Section 18.1 along the exact flow, though Section 18.1 does not need it, as it passes through the explicit flow. The same maximum principle, in the form of Lemma 16.3, gives the estimate below \(q_{\ast}\) in Proposition 16.4.
The approximate forecast converges at infinite resolution in negative Sobolev spaces, uniformly in \(N\) (to the same limit as the forecast \(\psi\)). The martingale part of \(Y\) has bracket \(\int H^2\), and the positive inequality \(H_q^2 \leqslant \frac{C}{q} C_q\) gives
where \(q + c |k|^2\) bounds the lattice symbol from below (aliases of the cell embedding only increase the frequency). The drifts are integrable at infinity in \(H\): the bounded-field drift is \(O (q^{- 5 / 2})\), the large-field drift is controlled by \(\int q^{7 / 2} \|b^{\text{l}} \|^2 \leqslant C \lambda^3 J_{\infty}\) and Cauchy–Schwarz, and \(\int \|H_q Z_q \| \mathrm{d} q \leqslant C \int q^{- 1} \|Z_q \| \leqslant C \lambda^{1 / 2} E_{\infty}^{1 / 2}\). More precisely, the squared drift tails beyond \(Q\) are \(O (Q^{- 3})\) (bounded-field), \(O (Q^{- 5 / 2}) \lambda^3 J_{\infty}\) (large-field) and \(O (Q^{- 3 / 2}) \lambda E_{\infty}\) (the \(HZ\) term), all at most \(Q^{- (s - \frac{1}{2})}\) for \(s < \frac{3}{2}\). By Doob's inequality, for \(\frac{1}{2} < s < \frac{3}{2}\),
| \(\displaystyle \sup_N \mathbb{E} \sup_{t \geqslant Q} \|Y_t - Y_Q \|^2_{H^{- s}} \leqslant C_s \hspace{0.17em} Q^{- (s - \frac{1}{2})} .\) | (17.3) |
Letting \(t \to \infty\) at fixed \(N\) (Lemma 16.1) this holds with \(Y_t\) replaced by \(\Phi_{\infty}\).
The field at the lower scale. As in the proof of Proposition 16.4, \(\|Y_{q_{\ast}} \|_2\) has all moments, uniformly in \(N\). So \(\sup_N \mathbb{E} \| \iota_N \Phi^N_{\infty} \|_{H^{- s\prime}}^2 < \infty\) for \(\frac{1}{2} < s\prime < \frac{3}{2}\), and these spaces embed compactly in \(H^{- s}\) for \(s > s\prime\):
Corollary
For the moments: the drift integrals have all moments by
The threshold \(s > \frac{1}{2}\) is that of the free field in \(d = 3\): the interacting field is no rougher than the Gaussian one. At every finite resolution its part \(V\) is smoother (\(H^1\)).
Theorem 16.2 gives only stretched exponential moments of the energies. Hairer and Steele [HSt22] showed that the measure has quartic exponential tails, as its formal density suggests, by tilting it and using a priori bounds for the tilted dynamics. Here is a proof in the language of this lecture, through linear sources: the filter is available for every prior, and the noise bound does not depend on the prior.
Let \(f \in H_N\), \(h \in \mathbb{R}\), and let \(\hat{\nu} \propto \mathrm{e}^{h \langle \varphi, f \rangle} \nu_N\), which has all moments at fixed \(N\). Let \(\Phi_q\) be the Polchinski process with terminal law \(\hat{\nu}\), i.e. the bridge (10.6) built on \(\hat{\Phi} \sim \hat{\nu}\), \(K_q \Phi_q = (q - q_0) \hat{\Phi} + B_{q - q_0}\), and \(\hat{\psi}_q =\mathbb{E}_q \hat{\Phi}\). Keep the force, and shift the field in the coordinate equation:
| \(\displaystyle K_q Y_q + \bar{\mathcal{F}}_q (Y_q) = K_q \Phi_q + hf, \quad Z_q = \hat{\psi}_q - Y_q . \) | (17.4) |
Proposition
Proof. This is the flow restarted at \((q_0, x)\) with \(x = hC_{q_0} f\): then \(\nu^{[q_0, x]} = \hat{\nu}\) and \(K_q \Phi_q + hf = K_{q_0} x + (q - q_0) \hat{\Phi} + B_{q - q_0}\). So the system and the boundary are as in Section 16.3; the extra term in the field equation is \((q - q_0) d_q + K_{q_0} d_q = hf\) with \(d_q = hC_q f\). Since \(\|d_q \|_{\infty} \leqslant |h| \|f\|_{\infty} / q \leqslant r_q / 64\) for \(q \geqslant q_1\), as \(64 < 70\), the proof of Proposition 16.4 applies with no range below the threshold. The backward estimate and the closure only improve with \(q_1\).\(\Box\)
There is also an exact identity with no cube and no derivative. As \(\eta_q = K_q \Phi_q - (q - q_0) \hat{\psi}_q\) and \(K_q \Phi_q = (q - q_0) \hat{\Phi} + B_{q - q_0}\) (here \(\eta\) is the unshifted noise, \(\eta_q =\mathbb{E}_q [B_{q - q_0}]\)), for every prior and \(q > q_0\),
| \(\displaystyle \hat{\Phi} = Y_q + Z_q + \frac{\eta_q - B_{q - q_0}}{q - q_0} . \) | (17.5) |
Theorem
| \(\displaystyle \mathbb{E} | \langle \Phi_{\infty}^N, f \rangle | \leqslant C \|f\|_{\ast}, \quad \mathbb{E} \exp (\beta \langle \Phi_{\infty}^N, f \rangle^4 /\|f\|_{\ast}^4) \leqslant C. \) | (17.6) |
Consequently, \(\sup_N \mathbb{E} \exp (\beta_{\rho} \| \iota_N \Phi_{\infty}^N \|_{H^{- \rho}}^4) < \infty\) for \(\rho > \frac{3}{2}\). The same bounds hold for the limit, by Theorem 18.5.
Proof. Let \(\|f\|_{\ast} = 1\) and \(q_h = \max (q_{\ast}, 2 q_0 + 1, (70 \lambda^{1 / 2} |h|)^{2 / 3})\). Put \(X = \langle \hat{\Phi}, f \rangle\). By (17.5), \(|Y| \leqslant r_q + |t_q |\) and \(q - q_0 \geqslant q / 2\),
Average over \([q_h, 2 q_h]\). By Proposition 17.3, \(\hat{\mathbb{E}} J_{\infty} \leqslant C\) on \([q_h, \infty)\); since \(\lambda (2 q_h)^{- 3 / 2} \int_{q_h}^{2 q_h} \|t_q \|_6^6 \hspace{0.17em} \mathrm{d} q \leqslant J_{\infty}\), Hölder's inequality gives the average of \(\hat{\mathbb{E}} \|t_q \|_6\) at most \(C (q_h^{1 / 2} / \lambda)^{1 / 6}\). Also \(\hat{\mathbb{E}} \|Z_q \|_2 \leqslant Cq^{- 5 / 4}\), and the last term has expectation at most \(Cq^{- 1 / 2}\) by Lemma 13.2. So \(\hat{\mathbb{E}} |X| \leqslant Cr_{q_h} + C \leqslant C (1 + |h|)^{1 / 3}\). With \(L (h) = \log \mathbb{E} \mathrm{e}^{h \langle \Phi_{\infty}, f \rangle}\) we have \(L' (h) = \hat{\mathbb{E}} X\) at fixed \(N\), so \(L (h) \leqslant C (|h| + |h|^{4 / 3})\), and Chernoff's inequality gives \(\mathbb{P} (| \langle \Phi_{\infty}, f \rangle | > R) \leqslant 2 \mathrm{e}^{- cR^4}\) for \(R \geqslant R_0\).
For the norm, take a real Fourier basis \(f_k\) and \(w_k = (1 + |k|^2)^{- \rho}\), with \(W = \sum w_k < \infty\). As \(\langle \iota_N \varphi, f_k \rangle = \langle \varphi, j_N f_k \rangle\) and \(\|j_N f_k \|_{\ast} \leqslant C\), the bound applies to \(z_k = \langle \iota_N \Phi_{\infty}, f_k \rangle\). Cauchy–Schwarz gives \(\left( \sum w_k z_k^2 \right)^2 \leqslant W \sum w_k z_k^4\), and Jensen's inequality concludes.\(\Box\)
The scale \(q_h \sim |h|^{2 / 3}\) is where the cube at its threshold, \(qr_q\), dominates the source; it plays the role of the time in coming down from infinity. On one site \(L (h) \sim \frac{3}{4} (\lambda / 3)^{- 1 / 3} h^{4 / 3}\), so the powers are sharp there. The moments with \(\rho > \frac{3}{2}\) are at a regularity far from the free threshold. At the threshold we have the Gaussian order, by a quadratic tilt.
Theorem
Proof. Let \(\frac{1}{2} < s < \frac{3}{2}\), \(W = \frac{\beta}{2} \| \iota_N \varphi \|_{H^{- s}}^2\), \(\hat{\nu} \propto \mathrm{e}^W \nu_N\), with no shift. As in the proof of Lemma 16.1, with \(V_N - W\) in place of \(V_N\), (16.3) gives \(TZ_T \to DW (\hat{\Phi})\) at fixed \(N\), with \(\|DW\|_2 \leqslant \beta \| \iota_N \varphi \|_{H^{- s}}\). Let \(x = \hat{\mathbb{E}} \| \iota_N \hat{\Phi} \|_{H^{- s}}^2 < \infty\). Then (15.4) with \(p = 1\) gives \(\hat{\mathbb{E}} (E_{\infty} + J_{\infty}) \leqslant C (1 + \beta^2 x)\), and the argument for the field at the lower scale gives \(\hat{\mathbb{E}} \|Y_{q_{\ast}} \|_2^2 \leqslant C (1 + \beta^2 x)\). Integrating the forward equation on \([q_{\ast}, \infty)\), with (17.2) for the martingale and Cauchy–Schwarz in \(q\) for the drifts, \(x \leqslant C_s (1 + \beta^2 x)\). So \(x \leqslant 2 C_s\) for small \(\beta\). Thus \(\hat{\nu} (A) \geqslant \frac{1}{2}\) for the ball \(A\) of radius \(K\), \(K^2 = 4 C_s\), in \(H^{- s}\). Since \(\hat{\nu} (A) \leqslant \mathcal{Z}^{- 1} \mathrm{e}^{\beta K^2 / 2}\), this bounds \(\mathcal{Z}=\mathbb{E} \mathrm{e}^W \leqslant 2 \mathrm{e}^{\beta K^2 / 2}\).\(\Box\)
Exercise
Exercise
Exercise
Exercise
The coefficients \(M^N_q\), \(\ell^{[j], N}_q\), \(H^N_q (y)\), \(b^N_q (y)\) are constructed at each lattice. Their uniform bounds (Proposition 11.1) do not by themselves identify a limit: a weakly convergent vertex cannot in general be contracted against a varying covariance. The three tools are:
Weak vertex measures. Derivative kernels with bounded rooted norms are signed measures with bounded mass; they converge weakly along subsequences, and the centred kernel \(\Theta_q\) converges in a weak topology controlled by its first moment. The limiting coefficients solve the same fixed-point problem, whose solution is unique in its ball; so the whole sequence converges.
Compact sandwich. If \(G_N \to G\) in Hilbert–Schmidt norm, and \(\textsf{B}_N\) are symmetric, uniformly bounded and converge weakly to \(\textsf{B}\), with \(\sup_N \|G_N \textsf{B}_N \| \leqslant \theta < 1\) and \(\|G \textsf{B} \| \leqslant \theta\), then \((I + G_N \textsf{B}_N)^{- 1} G_N \to (I + G \textsf{B})^{- 1} G\) in Hilbert–Schmidt norm. The free resolvent is the compact factor that turns weak convergence of the derivative of the force into strong convergence of the response.
Contraction against a moving covariance. The rows of the inverses are Hölder (any exponent \(a < \frac{1}{2}\)); with the Hilbert–Schmidt convergence given by the sandwich, the squared kernels \((H^N_q)^2\) converge uniformly to a continuous kernel. Weakly convergent vertices of bounded variation can therefore be contracted against them, and the loop steps of the recursion pass to the limit.
With these, if \(Y^N_q \to Y_q\) uniformly on \(\mathbb{T}^3\) for almost every \(q \in I\), with \(\sup_I \|Y^N \|_{\infty}\) bounded, in probability, then \(H^N_q (Y^N_q) \to H_q (Y_q)\) and \(b^N_q (Y^N_q) \to b_q (Y_q)\) in \(L^2 (I ; \text{HS})\) and \(L^2 (I ; H)\), in probability. By the resolvent identity \(H^N = (I - H^N D \bar{\mathcal{F}}^N) C^N\), for bounded \(y\), \(H^N\) is small in Hilbert–Schmidt norm on high modes, uniformly in \(N\); so the Fourier projection and \(j_N\) give the same limit, and \(\int_I \iota_N H^N (Y^N) \hspace{0.17em} \mathrm{d} W^N \to \int_I H (Y) \hspace{0.17em} \mathrm{d} W\) in \(H\), in probability, when \(W^N\) is the projection of \(W\), and the processes are adapted to a filtration for which \(W\) is a Brownian motion. For \(q < q_{\ast}\) this holds with the frozen coefficients, as \(\mathcal{U}\) in (12.19) is the loop part of the defect, and \(Y\) is continuous across \(q_{\ast}\) although \(b\) jumps.
Compactness would give limit points, and nothing in the FBSDE selects among them. A change of measure does better, following the idea of Gubinelli and Meyer for sine–Gordon [GM24]: the exact flow is an explicit flow with control \(Z\), and that control has finite relative entropy.
Let \(y = y_q (x)\) solve \(K_q y + \bar{\mathcal{F}}_q (y) = K_q x\), let \(\bar{f}_q (x) = K_q (y - x)\) be the explicit force in the field variable, and recall the exact force \(F_q = - DV_q\) of Section 16.3. Differentiating the coordinate equation in \(q\) and \(x\) gives the Burgers equation with a source,
| \(\displaystyle \partial_q \bar{f} + \frac{1}{2} \text{Ctr}_{C_q^2} D^2 \bar{f} + D \bar{f} [C_q^2 \bar{f}] = - K_q H_q \mathcal{D}_q \circ y. \) | (18.1) |
Up to here we have needed only forces. To compare the laws of the two flows we need, for the first time, a scalar. Since \(D \bar{\mathcal{F}}\) is symmetric, \(\bar{\mathcal{F}}\) is a gradient, and so are \(\bar{f}_q\) and the defect \(\mathcal{D}_q\) (as \(\frac{1}{2} \text{Ctr}_{H^2} D^2 \bar{\mathcal{F}} = - \frac{1}{2} D \text{Tr} H\)). Let
so that \(De_q =\mathcal{D}_q\), \(D \bar{V}_q = - \bar{f}_q\), \(e_q (0) = \bar{V}_q (0) = 0\). Then (18.1), together with \(Dy = H_q K_q\), is the gradient of
where the constant is read off at \(x = 0\), as \(D^2 \bar{V} (0) = K_q - K_q H_q (0) K_q\). Here \(\bar{V}\) is the value function of the explicit flow, in the sense of Section 8.5 of Lecture 4, and \(e\) is its running cost. This is the only place where a potential enters, and it is unavoidable: Girsanov alone gives a density in terms of the unknown \(Z\), and only the identity \(\mathcal{D}= De\) makes it explicit.
So \(\bar{V}\) solves the Polchinski equation up to its defect. Since \(C_s^2 D \bar{V}_s (x) = C_s (x - y_s (x))\), the explicit flow \(\mathbb{R}^{q, x}\) from \(x\) at scale \(q\) is
| \(\displaystyle \hspace{0.17em} \mathrm{d} x = - C_s (x - y_s (x)) \hspace{0.17em} \mathrm{d} s + C_s \hspace{0.17em} \mathrm{d} W, \quad x_q = x. \) | (18.4) |
Its coordinate \(Y = y_s (x_s)\) solves \(\hspace{0.17em} \mathrm{d} Y = b (Y) \hspace{0.17em} \mathrm{d} s + H (Y) \hspace{0.17em} \mathrm{d} W\), \(b = - H\mathcal{D}\): indeed \(\hspace{0.17em} \mathrm{d} (K_s x) = Y \hspace{0.17em} \mathrm{d} s + \hspace{0.17em} \mathrm{d} W\), and one applies Itô's formula to \(K_s Y + \bar{\mathcal{F}}_s (Y) = K_s x\). It contains no \(Z\). All this holds for all \(q \geqslant q_0\); below \(q_{\ast}\) the defect is (12.19).
Lemma
Proof. On the ball \(\mathcal{D}_s =\mathcal{D}_s^o\), so \(|e_s (\pi_s y) | \leqslant C \lambda^5 s^{- 3} \| \pi_s y\|_4^4\) by the primitive formula and (11.12). With \(z_{\theta} = \pi_s y + \theta (y - \pi_s y)\), \(e_s (y) - e_s (\pi_s y) = \int_0^1 \langle \mathcal{D}_s (z_{\theta}), y - \pi_s y \rangle \hspace{0.17em} \mathrm{d} \theta\), and \(y - \pi_s y\) is supported on the set \(\mathcal{A}\) where \(|y| > r_s\), with norm at most \(\|t_s \|_2\). Write \(De = D \kappa \mathcal{D}^{\text{o}} \circ \kappa +\mathfrak{D}\). Then \(|\mathcal{D}^{\text{o}} | \leqslant \textsf{S}_4 (\mathcal{D}^{\text{o}}) (2 r_s)^3 \leqslant C \lambda^{7 / 2} s^{- 3 / 2}\) and \(|\mathcal{A}|^{1 / 2} \leqslant r_s^{- 1} \|t_s \|_2\), so the first term contributes at most \(C \lambda^4 s^{- 2} \|t_s \|_2^2\). By the term-by-term bounds behind Proposition 12.2 (the four groups of Section 12.3 of Lecture 6, proved in Section 21.3 of the Supplement), which bound \(\mathfrak{D}\) before multiplication by \(H\) (the bound stated for \(b^{\text{l}} = - H\mathfrak{D}\) would not suffice, as \(H^{- 1}\) is unbounded), \(\|\mathfrak{D}_s (z)\|_2 \leqslant Cg_s (\|t_s (z)\|_2 + r_s^{- 1} \|z^2 \chi_s (z)\|_2)\); since \(|z_{\theta} | \leqslant |y|\) and \(z_{\theta}\) has size above \(r_s\) only on \(\mathcal{A}\), the second term contributes at most \(Cg_s (\|t_s \|_2^2 + r_s^{- 1} \|t_s \|_4^2 \|t_s \|_2)\). On the support of \(t_s\) we have \(|t_s | \geqslant r_s\), so \(\|t_s \|_2 \leqslant r_s^{- 2} \|t_s \|_6^3\) and \(\|t_s \|_4^2 \leqslant r_s^{- 1} \|t_s \|_6^3\). All these are at most \(Cg_s r_s^{- 4} \|t_s \|_6^6 = C \lambda^3 s^{- 5 / 2} \|t_s \|_6^6\).\(\Box\)
With \(\Delta = V - \bar{V}\) (\(\Delta\) is not the Laplacian in this section), \(\mathcal{C}_N (q) = \int_q^{\infty} c (s) \hspace{0.17em} \mathrm{d} s\) and \(A_N (q, x) = V_q (x) - \bar{V}_q (x) -\mathcal{C}_N (q)\), subtracting (18.3) from the Polchinski equation gives
| \(\displaystyle \partial_s \Delta + \frac{1}{2} \text{Tr} (C_s^2 D^2 \Delta) - \langle C_s^2 D \bar{V}_s, D \Delta \rangle - \frac{1}{2} \|C_s D \Delta \|_2^2 + e_s \circ y_s + c (s) = 0. \) | (18.6) |
This is a Hamilton–Jacobi–Bellman equation with the control \(u\), added as a drift \(C_s u_s\) to the explicit flow, \(\hspace{0.17em} \mathrm{d} Y = (b (Y) + H (Y) u) \hspace{0.17em} \mathrm{d} s + H (Y) \hspace{0.17em} \mathrm{d} W\), and running cost \(e + c + \frac{1}{2} \|u\|^2\), with optimal feedback \(u^{\ast} = - C_s D \Delta_s\). Moreover \(- C_s D \Delta_s = C_s (F_s - \bar{f}_s) = Z_s\), since \(F = K (\psi - x)\) and \(\bar{f} = - D \bar{V} = - K (x - y)\). So the exact flow is the explicit flow with control \(Z\).
Theorem
Further,
| \(\displaystyle \text{Ent} (\mathbb{P}^{q, x} |\mathbb{R}^{q, x}) = \frac{1}{2} \int_q^{\infty} \mathbb{E}^{q, x} \|Z_s \|_2^2 \hspace{0.17em} \mathrm{d} s, \) | (18.8) |
| \(\displaystyle A_N (q, x) = \text{Ent} (\mathbb{P}^{q, x} |\mathbb{R}^{q, x}) +\mathbb{E}^{\mathbb{P}^{q, x}} \int_q^{\infty} e_s (Y_s) \hspace{0.17em} \mathrm{d} s, \) | (18.9) |
and so
Uniformly in \(N\), for \(\|x\|_{\infty} \leqslant R\) and \(T \geqslant q^{\vee}\),
The integrals over \([q, q_{\ast}]\), if \(q < q_{\ast}\), are at most \(C_R\). In particular \(|A_N (q, x) | \leqslant C_R\).
Proof. Density on \([q, T]\). Both are absolutely continuous with respect to the free flow from \(x\), \(\hspace{0.17em} \mathrm{d} \xi = C_s \hspace{0.17em} \mathrm{d} W\). As \(\mathrm{e}^{- V}\) is harmonic the first density is \(\mathrm{e}^{- V_T (\xi_T) + V_q (x)}\). By (18.3) and Itô's formula the second is \(\exp \left( - \bar{V}_T (\xi_T) + \bar{V}_q (x) + \int_q^T (e_s (y_s (\xi_s)) + c (s)) \hspace{0.17em} \mathrm{d} s \right)\); it is a true martingale since the drift is Lipschitz at fixed \(N\). So
Entropy on \([q, T]\). Under \(\mathbb{P}^{q, x}\) the explicit flow has the extra drift \(C_s Z_s\), so \(\log M_T = \int_q^T \langle Z_s, \hspace{0.17em} \mathrm{d} W_s \rangle + \frac{1}{2} \int_q^T \|Z_s \|_2^2 \hspace{0.17em} \mathrm{d} s\), and \(\text{Ent}_T = \frac{1}{2} \mathbb{E} \int_q^T \|Z\|_2^2\), as the stochastic integral is a true martingale at fixed \(N\). By Proposition 16.4 and \(\mathbb{E} \|Z_s \|_2^2 \leqslant C_R s^{- 5 / 2}\), (16.10), \(\sup_T \text{Ent}_T \leqslant C_R\). So \(M_T\) is uniformly integrable under \(\mathbb{R}^{q, x}\), and \(\mathbb{P}^{q, x} \ll \mathbb{R}^{q, x}\) on \([q, \infty)\) with density \(M_{\infty} = \text{lim}_T M_T\), and (18.8) holds.
The limit of \(M_T\). Both laws have, at fixed \(N\), \(x_T \to x_{\infty}\) almost surely. Under \(\mathbb{P}^{q, x}\), \(x_T \to \hat{\Phi}\), from \(x_T = C_T (K_q x + (T - q) \hat{\Phi} + B'_{T - q})\). Under \(\mathbb{R}^{q, x}\), \(\hspace{0.17em} \mathrm{d} Y = b (Y) \hspace{0.17em} \mathrm{d} s + H (Y) \hspace{0.17em} \mathrm{d} W\) with \(\|b (Y)\|_2 \leqslant C \lambda s^{- 3 / 2} \|Y\|_2\) and \(\|H\| \leqslant C / s\), so \(\sup_s \|Y_s \|_2\) is finite and \(Y_s\) converges almost surely, the drift being integrable and the martingale bounded in \(L^2\); and \(x - y = \varrho_s (y) + \frac{\lambda}{3} C_s y^3 = O_N (s^{- 1} (1 +\|y\|_{\infty}^3)) \to 0\). Then \(\Delta_T (x_T) \to 0\): at fixed \(N\) the coefficients converge with rates and \(y - x = O_N (T^{- 1} (\|x\|_{\infty} +\|x\|_{\infty}^3))\), so \(\bar{V}_T \to V_N\), and \(V_T \to V_N\) by Gaussian integration, uniformly on bounded sets. By the bounds below \(\int_q^{\infty} |e_s (Y_s) | \hspace{0.17em} \mathrm{d} s < \infty\) almost surely under both laws, and \(c\) is integrable at fixed \(N\). So \(M_{\infty} = \exp \left( \Delta_q (x) -\mathcal{C}_N (q) - \int_q^{\infty} e \right) = \mathrm{e}^{A_N} \mathrm{e}^{- \int e}\), which is positive; hence the equivalence and (18.7), the second formula by \(\mathbb{E}^{\mathbb{R}} M_{\infty} = 1\).
The identity. Take \(\mathbb{E}^{\mathbb{P}}\) of \(\log M_{\infty}\) in (18.7): this is (18.9), the integrability coming from (18.11). The left inequality in (18.10) is \(\text{Ent} \geqslant 0\), the right one Jensen's inequality in (18.7). So the exact and explicit potentials are compared using only expectations of the defect and the entropy of the control.
The expectations. For \(s < q_{\ast}\) use (12.20), so \(|e_s (y) | \leqslant C \|y\|_2^2\) by (18.2): under \(\mathbb{P}^{q, x}\) by (16.10); under \(\mathbb{R}^{q, x}\) by Itô's formula for \(\|Y\|_2^2\), the bounds (12.20) and \(\|Y_q \|_2 \leqslant 6 R\). So these contribute at most \(C_R\). For \(s \geqslant q_{\ast}\) use Lemma 18.1, \(|e_s (y) | \leqslant C \lambda^5 s^{- 3} \| \pi_s y\|_4^4 + C \lambda^3 s^{- 5 / 2} \|t_s (y)\|_6^6\). Under \(\mathbb{P}^{q, x}\): the second term integrates on \([T, \infty)\) to at most \(C \lambda^2 T^{- 1} J_{\infty}\). For the first, with \(\| \pi_s Y\|_4^4 \leqslant r_s^2 \|Y\|_2^2\), (16.9) gives a bound \(C_R T^{- 1 / 2}\). Under \(\mathbb{R}^{q, x}\): with \(\varsigma_s = Y_s - Y_q\), by the linear bound \(\|b (Y)\|_p \leqslant C \lambda s^{- 3 / 2} \|Y\|_p\) of Proposition 12.2, valid for every \(p\), \(\text{diag} H^2 \leqslant Cs^{- 1 / 2}\) and Itô's formula, \(\mathbb{E} \| \varsigma_s \|_j^j \leqslant C (s^{j / 4} + (g_{q^{\vee}} R)^j)\) for \(j = 2, 6, 12\), with \(C\) depending on \(q_{\ast}\) if \(q < q_{\ast}\), by (12.20) on \([q, q_{\ast}]\); in that case read \(g_q\) below as \(g_{q_{\ast}}\), only \(C_R\) being claimed. The first term gives \(C \lambda^5 T^{- 2} R^4 + C \lambda^4 T^{- 1 / 2} (1 + g_q^2 R^2 T^{- 1 / 2})\). For the second, when \(s \geqslant q_R / C\), \(\|t_s \|_6^6 \leqslant Cr_s^{- 6} \| \varsigma_s \|_{12}^{12}\) as before, giving \(C \lambda^6 T^{- 3 / 2}\) and terms in \(g_q R\) of higher decay. When \(s < q_R / C\), \(\|t_s \|_6^6 \leqslant C (R^6 +\| \varsigma_s \|_6^6)\), whose integral with the weight \(\lambda^3 s^{- 5 / 2}\) on \([T, q_R / C]\) is at most \(C \lambda^3 (T^{- 3 / 2} R^6 + (g_q R)^6 T^{- 3 / 2} + \log_+ (q_R / T))\). Since \(\log_+ (q_R / T) \leqslant C_R T^{- 1 / 2}\), this is (18.11).\(\Box\)
Couple the lattices by common Fourier Gaussians, \(W^N\) being the projection of a cylindrical \(W\) on a fixed probability space. The consistency of the fixed-scale coefficients of Section 18.1 gives the following, along \(b_N \to b\).
Lemma
Proof. For \(y\): boundedness by the maximum principle, equicontinuity by Lemma 16.3 and translation covariance, uniqueness of the coordinate equation among continuous \(y\) by testing with the difference, as \(y - x \in H^1\). For \(e\): \(e_s (0) = 0\), so \(e_s (y) = \int_0^1 \langle \mathcal{D}_s (ty), y \rangle \hspace{0.17em} \mathrm{d} t\). By the consistency of the coefficients (Theorem 31.2 of the Supplement), \(\mathcal{D}^N_s (\phi_N)\) converges weakly in \(L^2\) at each \(s\) for smooth bounded \(\phi\), and uniformly in \(N\), \(\|\mathcal{D}^N_s (y) -\mathcal{D}^N_s (z)\|_2 \leqslant C (1 +\|z\|_{\infty}) (\|y - z\|_2 +\|y^2 - z^2 \|_2)\). A three-term approximation extends the weak convergence to uniformly convergent fields, and dominated convergence in \(t\) gives the claim. Moreover \(|e^N_s (y) | \leqslant Cg_s \|y\|_2^2\) by the global linear bound on \(\mathcal{D}\) behind Proposition 12.2 (Lemma 21.2 of the Supplement), which dominates on \([q, T]\). For \(s < q_{\ast}\) the same applies to \(\mathcal{U}\) in (12.19), and \(\|y\|_2^2\) is continuous; for \(y_s\) use (12.18) and the convergence of the kernel of \(C_{q_{\ast}}\) in \(L^1\).\(\Box\)
By Lemma 16.3, \(x = \xi + v\) with \(\xi_t = x_q + \int_q^t C_s \hspace{0.17em} \mathrm{d} W_s\) and \(v\) solving an ODE on \(C (\mathbb{T}^3)\), uniquely, for each path \(\xi \in C ([q, T] ; L^{\infty})\). So the explicit flow \(\mathbb{R}^{q, x}\) is a continuum strong solution, adapted to \(W\), for continuous \(x\). By Lemma 18.3 and the continuity of the ODE, if \(\iota_N x_N \to x\) uniformly, then along the coupling \(\sup_{s \leqslant T} \| \iota_N x^N_s - x_s \|_{\infty} \to 0\) almost surely, since \(\mathbb{E} \sup_{s \leqslant T} \| \iota_N \xi^N_s - \xi_s \|_{\infty}^p \leqslant C_p N^{- \delta p}\) by Kolmogorov interpolation between the covariance difference and the Hölder bounds, and Borel–Cantelli. Testing, \(\langle Y_s, h \rangle\) converges as \(s \to \infty\) in \(L^2\) for \(h \in L^2\), uniformly in \(N\), since \(\|H_s h\|_2 \leqslant Cs^{- 1} \|h\|_2\) and \(\|b\|_2 \leqslant C \lambda s^{- 3 / 2} \|Y\|_2\). So \(\langle Y_{\infty}, h \rangle\) is defined; by (17.2) and the Itô bound on \(\mathbb{E} \|Y_s \|_2^2\), \(Y_s\) converges also in \(H^{- s'}\), \(s' > \frac{1}{2}\), in \(L^2 (\mathbb{R}^{q, x})\), uniformly in \(N\).
Theorem
The same holds for bounded functionals of the path \((x_s)_{s \leqslant T}\) and finitely many \(\langle \varphi, h_i \rangle\) jointly, continuous for the uniform norm, and for \(O (\varphi) = \langle \varphi, h \rangle\), \(h \in L^2\). So \(A\) and \(\Pi_q O (x)\) are jointly continuous in \((q, x) \in [q_0, \infty) \times C (\mathbb{T}^3)\), also for \(O = \langle \cdot, h \rangle\). We write \(\langle m_q (x), h \rangle = \Pi_q \langle \cdot, h \rangle (x)\), the limit decoupling field; \(\|m_q (x)\|_2 \leqslant C_R\) by Proposition 16.4.
Proof. Let \(a_N = \exp \left( - \int_q^{\infty} e^N_s (Y^N_s) \hspace{0.17em} \mathrm{d} s \right)\), \(f_N = \mathrm{e}^{A_N} a_N\). On \([q, T]\) the integrals converge almost surely by Lemma 18.3, since the paths are bounded; the tail on \([T, \infty)\) is small in \(L^1\) uniformly in \(N\) by (18.11). So \(a_N \to a = \exp \left( - \int_q^{\infty} e \right)\) in probability. By (18.8), (16.9) and (16.10), \(\mathbb{E}f_N \log f_N \leqslant C_R\), so \((f_N)\) is uniformly integrable by de la Vallée Poussin's criterion, and \(|A_N | \leqslant C_R\) by Theorem 18.2. Along any subsequence with \(A_N \to A\), \(f_N \to \mathrm{e}^A a\) in \(L^1\), so \(\mathrm{e}^{- A} =\mathbb{E}a\). Thus the limit is unique and \(A_N \to A\). As \(\langle Y^N_{\infty}, h \rangle \to \langle Y_{\infty}, h \rangle\) in probability, \(L^1\) convergence of \(f_N\) gives (18.12) for bounded continuous \(O\) and, the paths converging uniformly along the coupling, for the joint functionals. For \(\langle \varphi, h \rangle\) use also the uniform second moment of \(\langle \hat{\Phi}, h \rangle\) under \(\mathbb{P}^{q, x_N}\), from the system (1) and (16.9). Continuity: the limit of \(\Pi^N\) along every uniformly convergent sequence exists, so the limit function is continuous in \(x\). If \((q_n, x_n) \to (q, x)\), the flows driven by the same \(W\) converge uniformly on compact scales by Lemma 16.3, \(\int_{q \wedge q_n}^{q \vee q_n} |e_s (Y_s) | \hspace{0.17em} \mathrm{d} s \to 0\) by the bounds on the defect, and the tails and the entropy are uniform; the same argument gives joint continuity.\(\Box\)
Theorem
With \(V_N (0) = 0\) and \(\mu_C\) the Gaussian measure of covariance \(C_{q_0}\), the renormalised free energy converges:
Proof. This is Theorem 18.4 at \((q, x) = (q_0, 0)\), as \(\mathbb{P}^{q_0, 0}\) is the flow for \(\nu_N\), and \(\bar{V}_{q_0} (0) = 0\), \(V_{q_0} (0) = - \log \int \mathrm{e}^{- V_N} \hspace{0.17em} \mathrm{d} \mu_C\). With the tightness of Corollary 17.2 this identifies the limit along the whole sequence.\(\Box\)
The divergent constant has not disappeared: it is \(\mathcal{C}_N (q_0)\) in (18.14), and it does not enter (18.13). Exercise 18.9 computes it in the Gaussian case.
We now read off the limit FBSDE from the density. Let \(\mathbb{R}=\mathbb{R}^{q_0, 0}\), \(\mathbb{P}= f\mathbb{R}\) with \(f = \mathrm{e}^{A (q_0, 0)} \mathrm{e}^{- \int_{q_0}^{\infty} e}\), on the paths of \(x\). Let \(\Phi = Y_{\infty}\), \(\Phi_q = x_q\), tested with smooth functions, and \(\mathcal{F}_q = \sigma (x_s : s \leqslant q)\).
Theorem
The filtering model. \(\Phi \sim \nu\), and \(x_q = (q - q_0) C_q \Phi + C_q B_{q - q_0}\) with \(B\) a cylindrical Brownian motion independent of \(\Phi\).
The forecast. The conditional law of \(\Phi\) given \(\mathcal{F}_q\) is \(\Pi_q (\Phi_q, \cdot)\). So for smooth \(h\),
| \(\displaystyle \langle \psi_q, h \rangle : =\mathbb{E} [\langle \Phi, h \rangle |\mathcal{F}_q] = \langle m_q (\Phi_q), h \rangle, \) | (18.15) |
which is a function of \(x_q\), and \(\psi_q\) is the conditional mean of the terminal field.
The FBSDE. \(W_q = K_q x_q - \int_{q_0}^q \psi_s \hspace{0.17em} \mathrm{d} s\) is a cylindrical Brownian motion for \((\mathcal{F}_q)\). With \(Y_q = y_q (x_q)\), \(Z = \psi - Y\), and for \(q \geqslant q_0\),
where \(\Xi = \text{Cov} - H (Y)\), \(\psi = \int \text{Cov} \hspace{0.17em} \mathrm{d} W\) with no orthogonal part, and \(\text{Cov}\) is the conditional covariance,
| \(\displaystyle \langle \text{Cov}_q h, k \rangle =\mathbb{E} [\langle \Phi, h \rangle \langle \Phi, k \rangle |\mathcal{F}_q] - \langle \psi_q, h \rangle \langle \psi_q, k \rangle . \) | (18.17) |
Moreover \(Y_{q_0} = Z_{q_0} = 0\), and \(\mathbb{E} \|Z_q \|_2^2 \leqslant Cq^{- 5 / 2}\) for large \(q\).
The terminal value. \(Y_q \to \Phi\) in \(H^{- s}\) in mean square, for every \(s > \frac{1}{2}\).
The lattice. Along the whole sequence, in law and jointly with \(\Phi^N_{\infty}\): \(x^N\) converges uniformly on compact sets of scales and space, \(Y^N_q\) uniformly in space at each \(q\), \(\langle \psi^N_q, h \rangle\), \(\langle Z^N_q, h \rangle\) at each \(q\), the innovations \(W^N\) in \(C (I ; H^{- \vartheta})\), \(\vartheta > \frac{3}{2}\), to \(W\). The energies \(E_{\infty}, J_{\infty}\) satisfy the bounds of Theorem 16.2 in the limit.
Proof. (a). By Theorem 18.4 at \((q_0, 0)\), the pair \((x^N, \Phi^N_{\infty})\) under the exact law converges in law to \((x, \Phi)\) under \(\mathbb{P}\). At each \(N\), \(K_q \Phi^N_q - (q - q_0) \Phi^N_{\infty}\) is a Brownian motion independent of \(\Phi^N_{\infty}\); test with \(j_N h\), as \(\iota_N K_q j_N h\) converges in every Sobolev norm. So \(\langle B_t, h \rangle\) for smooth \(h\) are jointly Gaussian, independent of \(\Phi\), with covariance \((s \wedge t) \langle h, k \rangle\); by density \(B\) is a cylindrical Brownian motion, with paths in \(H^{- \vartheta}\), \(\vartheta > \frac{3}{2}\). Moreover \(\mathcal{F}_q \subset \sigma (\Phi, B_r : r \leqslant q - q_0)\), as \(x_r = (r - q_0) C_r \Phi + C_r B_{r - q_0}\).
(b). Under \(\mathbb{R}\) the flow is Markov, and by Theorem 18.4 at \((t, x_t)\),
| \(\displaystyle D_t : =\mathbb{E}^{\mathbb{R}} [f|\mathcal{F}_t] = \exp (A (q_0, 0) - A (t, x_t) - \int_{q_0}^t e_s (Y_s) \hspace{0.17em} \mathrm{d} s), \) | (18.18) |
and \(\mathbb{E}^{\mathbb{P}} [O (\Phi) |\mathcal{F}_t] =\mathbb{E}^{\mathbb{R}} [fO (\Phi) |\mathcal{F}_t] / D_t = \Pi_t O (x_t)\). The right side of (18.18) is continuous in \(t\), so (18.18) holds for all \(t\) simultaneously, and \(D\) is continuous and positive.
(c): the forward equation. By Lemma 16.3 the flow is a strong solution, and \(x\) and \(W^{\mathbb{R}}\) determine each other; so \(\mathcal{F}\) is a Brownian filtration under \(\mathbb{R}\). As \(f > 0\) has finite entropy, by lower semicontinuity from Theorem 18.2, martingale representation gives \(\hspace{0.17em} \mathrm{d} D = D \langle Z', \hspace{0.17em} \mathrm{d} W^{\mathbb{R}} \rangle\) with \(\mathbb{E}^{\mathbb{P}} \int \|Z' \|_2^2 = 2 \text{Ent} (\mathbb{P}|\mathbb{R})\), and \(W : = W^{\mathbb{R}} - \int Z'\) is a \(\mathbb{P}\)-Brownian motion for \(\mathcal{F}\) by Girsanov's theorem. Under \(\mathbb{R}\), the lattice equation \(\hspace{0.17em} \mathrm{d} Y = b (Y) \hspace{0.17em} \mathrm{d} s + H (Y) \hspace{0.17em} \mathrm{d} W^{\mathbb{R}}\) passes to the limit by Section 18.1, along the convergence of the coupling at each scale. So under \(\mathbb{P}\), \(\hspace{0.17em} \mathrm{d} Y = (b (Y) + H (Y) Z') \hspace{0.17em} \mathrm{d} s + H (Y) \hspace{0.17em} \mathrm{d} W\), and \(\mathrm{d} (K_s x_s) = (Y_s + Z'_s) \hspace{0.17em} \mathrm{d} s + \mathrm{d} W_s\).
The drift is the forecast. By (a), the increments of \(B\) after \(s\) are independent of \(\Phi\) and of \(\mathcal{F}_s\), so \(\mathbb{E} [\langle K_t x_t - K_s x_s, h \rangle |\mathcal{F}_s] = (t - s) \langle \psi_s, h \rangle\) for smooth \(h\). As \(\psi\) is a martingale, \(\langle K_q x_q, h \rangle - \int_{q_0}^q \langle \psi_u, h \rangle \hspace{0.17em} \mathrm{d} u\) is an \(\mathcal{F}\)-martingale. So is \(\langle W_q, h \rangle = \langle K_q x_q, h \rangle - \int_{q_0}^q \langle Y_u + Z'_u, h \rangle \hspace{0.17em} \mathrm{d} u\), where \(Y + Z'\) is locally in \(L^2 (\hspace{0.17em} \mathrm{d} u \hspace{0.17em} \mathrm{d} \mathbb{P}; L^2)\), by (16.9), (16.10) and lower semicontinuity. Their difference is a continuous martingale of finite variation, null at \(q_0\), so it vanishes. With a countable dense set of \(h\), \(\psi_u = Y_u + Z'_u\) for almost every \((u, \omega)\), where \(\psi_u = m_u (x_u)\) is defined at every scale. So \(Z : = \psi - Y = m (x) - y (x)\) is defined at every scale, \(Z' = Z\) almost everywhere, and \(W\) is the innovation. Moreover \(\mathbb{E} \| \psi_Q \|_2^2 \leqslant \text{liminf}_N \mathbb{E} \| \psi^N_Q \|_2^2 < \infty\), by Fatou's lemma along (e) and the same bounds, so \(\psi\) is square integrable.
Representation, with no orthogonal part. Let \(S = \langle \Phi, h \rangle\) and \(M =\mathbb{E}^{\mathbb{P}} [S|\mathcal{F}]\). Under \(\mathbb{R}\), \(N =\mathbb{E}^{\mathbb{R}} [fS|\mathcal{F}]\) is a Brownian integral, \(\hspace{0.17em} \mathrm{d} N = \langle n, \hspace{0.17em} \mathrm{d} W^{\mathbb{R}} \rangle\), and \(M = N / D\), so Itô's formula gives \(\hspace{0.17em} \mathrm{d} M = \langle n / D - MZ, \hspace{0.17em} \mathrm{d} W^{\mathbb{R}} - Z \hspace{0.17em} \mathrm{d} s \rangle = \langle n / D - MZ, \hspace{0.17em} \mathrm{d} W \rangle\). This defines \(\text{Cov} h\). Here \(S \in L^2 (\mathbb{P})\) by Theorem 18.4 and Fatou's lemma, so \(M\) is a true \(L^2\)-martingale and \(\mathbb{E} \int \| \text{Cov}_s h\|_2^2 \hspace{0.17em} \mathrm{d} s = \text{Var} S\). Summing over an orthonormal basis, \(\mathbb{E} \int_{q_0}^Q \| \text{Cov}_s \|_{\text{HS}}^2 \hspace{0.17em} \mathrm{d} s =\mathbb{E} \| \psi_Q \|_2^2\).
The covariance. For \(G\) bounded and \(\mathcal{F}_s\)-measurable and \(k\) smooth, \(W_t - W_s\) tested with \(k\) is \((t - s) \langle \Phi, k \rangle + \langle B_{t - q_0} - B_{s - q_0}, k \rangle - \int_s^t \langle \psi_u, k \rangle \hspace{0.17em} \mathrm{d} u\), and the term in \(B\) is independent of \((G, S)\). So \(\mathbb{E} [GS \langle W_t - W_s, k \rangle] = \int_s^t \mathbb{E} [GS (\langle \Phi, k \rangle - \langle \psi_u, k \rangle)] \hspace{0.17em} \mathrm{d} u\). By the representation and Itô's isometry the left side is \(\int_s^t \mathbb{E} [G \langle \text{Cov}_u h, k \rangle] \hspace{0.17em} \mathrm{d} u\). On the right, condition on \(\mathcal{F}_u \supset \mathcal{F}_s\). So the integral over \([q_0, \cdot]\) of the difference of the two sides of (18.17) is a continuous martingale of finite variation, hence null. This is (18.17) for almost every \((q, \omega)\), and \(\text{Cov}\) is symmetric and nonnegative, Hilbert–Schmidt almost everywhere.
The rest of (c). The equation for \(Z\) is the difference of those for \(\psi\) and \(Y\). At \(q_0\), \(x_{q_0} = 0\): so \(Y_{q_0} = 0\) since \(\bar{\mathcal{F}}\) is odd, and \(Z_{q_0} = \psi_{q_0} =\mathbb{E}_{\nu} \Phi = 0\). The bound on \(Z\) is weak lower semicontinuity from Theorem 16.2, by (e).
(d). (17.3) passes to the limit by lower semicontinuity.
(e). For the path and \(\Phi\) this is Theorem 18.4; for \(\psi^N = m^N (x^N)\) and \(Z^N\) use continuous convergence in the same theorem and the uniform bound of Proposition 16.4. Then \(W^N_q = K_q x^N_q - \int_{q_0}^q \psi^N_s \mathrm{d} s\) converges tested, and \(W^N\) is tight in \(C (I ; H^{- \vartheta})\) as a Brownian motion. For the energies, \(\zeta_q = \Phi_q - (q - q_0) C_q \psi_q\) and \(V_q = C_q \left[ (q - q_0) \psi_q - \frac{\lambda}{3} Y_q^3 \right]\) converge uniformly, since the rows of the kernel of \(C^N_q\) converge uniformly in \(L^2\), and along the coupling \(\psi^N_q = m^N_q (x^N_q)\) is bounded in \(L^2\) and converges weakly. The integrands of \(E\) and \(J\) are lower semicontinuous in these variables, and Fatou's lemma applies.\(\Box\)
Remark
The terminal law satisfies an integration by parts formula in which the renormalised cube appears only tested in expectation.
Theorem
Proof. At fixed \(N\), Gaussian integration by parts in the density \(\mathrm{e}^{- V_N - \frac{1}{2} \langle \varphi, K_{q_0} \varphi \rangle}\) gives, with \(x = \Phi^N_{\infty}\) and \(h_N = j_N h\),
Cell averaging commutes with lattice translations, so \(K_{q_0} j_N h = j_N (q_0 - \Delta^{\text{tr}}_N) h\) with \(\Delta^{\text{tr}}_N\) the finite-difference Laplacian acting on smooth functions, which converges to \(\Delta h\) in every Sobolev norm. The right side converges by Corollary 17.2 (weak convergence in \(H^{- s}\) and uniform moments), and the derivative term is a finite sum with converging coefficients \(\langle j_N h, j_N h_i \rangle \to \langle h, h_i \rangle\).\(\Box\)
This is the terminal case of the Dyson–Schwinger equation of Theorem 9.1, (9.8) of Lecture 5, for the limiting theory. It does not say that \(\mu_N \Phi + \frac{\lambda}{3} \Phi^3\) converges as a random distribution: only its expectation against cylinder functions is identified. This is consistent with the expectation of Lecture 5 (Remark 9.5) that the limiting force is an observable without a terminal representative; it is not proved here that no such representative exists. At every finite resolution, on the other hand, the force is explicit: \(F_q = K_q Z_q - \bar{\mathcal{F}}_q (Y_q)\) (Exercises 16.1 and 18.1).
Theorem
| \(\displaystyle K_{q_0} \Phi_q = J_q F_q + \eta_q, \) | (18.20) |
| \(\displaystyle \mathbb{E}D_{J_q h} G (\Phi_q) =\mathbb{E} [G (\Phi_q) \langle \eta_q, h \rangle] =\mathbb{E} [G (\Phi_q) (\langle \Phi_q, K_{q_0} h \rangle - \langle F_q, J_q h \rangle)], \) | (18.21) |
and \(\langle F, h \rangle, \langle \eta, h \rangle\) are centred martingales, with
and \(\mathbb{E} \mathrm{e}^{\langle \eta_q, h \rangle} \leqslant \mathrm{e}^{(q - q_0) \|h\|_2^2 / 2}\). Moreover:
The renormalised cube as an observable. For large \(q\), with the explicit force
| \(\displaystyle \| \langle F_q, h \rangle + \langle \bar{\mathcal{F}}_q (Y_q), h \rangle \|_{L^2 (\mathbb{P})} \leqslant C \|h\|_{H^2} q^{- 1 / 4} . \) | (18.22) |
So \(\langle F, h \rangle\) is the unique martingale asymptotically equivalent to the germ
in the sense of Lemma 5.4 of Lecture 3.
Infinite resolution. As \(q \to \infty\),
the right side of (18.19).
Along the scales. For \(g \in C_b^{\infty} (\mathbb{R}^k)\), \(G = g (\langle \Phi_{q_1}, h_1 \rangle, \ldots, \langle \Phi_{q_k}, h_k \rangle)\), \(q_i \leqslant q\),
so at every large resolution the renormalised cube closes the hierarchy, up to an error which vanishes as \(q \to \infty\).
Proof. The algebra and the integration by parts are those of Lecture 5, since by Theorem 18.6(a),(b), \(\eta_q =\mathbb{E}_q [B_{q - q_0}]\), with \(\Phi_q = J_q \Phi + C_q B_{q - q_0}\) and \(B\) independent of \(\Phi\). The martingale representation is \(\psi = \int \text{Cov} \hspace{0.17em} \mathrm{d} W\), and the exponential bound is conditional Jensen. For (18.22), \(F_q = K_q Z_q - \bar{\mathcal{F}}_q (Y_q)\), so its left side is at most \(\|K_q h\|_2 (\mathbb{E}\|Z_q \|_2^2)^{1 / 2}\), and Theorem 18.6(c) applies. For (18.23): by (18.22) with \(K_q J_q h = (q - q_0) h\), replacing \(- F_q\) by \(\bar{\mathcal{F}}_q (Y_q)\) in (18.21) costs \(O (q^{- 1 / 4})\). Moreover \(\langle \Phi_q, k \rangle = \langle \psi_q, J_q k \rangle + \langle \zeta_q, k \rangle\) with \(\mathbb{E} \langle \zeta_q, k \rangle^2 \leqslant \|k\|_2^2 / q\), and \(\psi_q \to \Phi\) tested in mean square, by the martingale property. So \(\Phi_q \to \Phi\) tested with smooth functions, and \(J_q h \to h\) in every Sobolev norm. (18.24) follows from (18.22) with \(J_q h\), as \(\|J_q h\|_{H^2} \leqslant \|h\|_{H^2}\).\(\Box\)
This is the renormalised cube: the cube of the forecast with its counterterms, at resolution \(q\). By (18.23) the two orders of limits, \(N \to \infty\) at the terminal resolution and \(q \to \infty\) after \(N\), give the same right side. What is not proved is that \(F\) is closed: (18.22) gives no bound on \(\langle F_q, h \rangle\) uniform in \(q\).
Along the exact flow the value \(A_t = A (t, x_t)\) solves a scalar backward equation, the integrated form of the vector one and the analogue of (4.13) of Gubinelli–Meyer. Indeed, by (18.18) and \(\hspace{0.17em} \mathrm{d} D = D \langle Z, \hspace{0.17em} \mathrm{d} W^{\mathbb{R}} \rangle\),
| \(\displaystyle A_t = \int_t^{\infty} (e_s (Y_s) + \frac{1}{2} \|Z_s \|_2^2) \hspace{0.17em} \mathrm{d} s + \int_t^{\infty} \langle Z_s, \hspace{0.17em} \mathrm{d} W_s \rangle . \) | (18.25) |
Definition
The forward equation here is \(\mathrm{d} (K_s x_s) = (Y_s + Z_s) \hspace{0.17em} \mathrm{d} s + \mathrm{d} W_s\): the forward equation of (18.16). The limit law is a solution, by the proof of Theorem 18.6, at \((q, x)\) in place of \((q_0, 0)\): \(\mathcal{E}_t = D_t^{- 1}\) is uniformly integrable under the exact law, closed by \(\hspace{0.17em} \mathrm{d} \mathbb{R}/ \hspace{0.17em} \mathrm{d} \mathbb{P}\), and \(A (t, x_t) \to 0\) as \(D_t \to f > 0\).
Theorem
Proof. Let \(\hspace{0.17em} \mathrm{d} \mathbb{Q}' =\mathcal{E}_{\infty} \hspace{0.17em} \mathrm{d} \mathbb{Q}\). Under \(\mathbb{Q}'\), \(W' = W + \int Z\) is a Brownian motion, and \(\hspace{0.17em} \mathrm{d} x = - C_s (x - Y) \hspace{0.17em} \mathrm{d} s + C_s \hspace{0.17em} \mathrm{d} W'\). By pathwise uniqueness (Lemma 16.3), \(x\) under \(\mathbb{Q}'\) has law \(\mathbb{R}^{q, x}\). By (18.25) at \(t = q\), \(\mathcal{E}_{\infty}^{- 1} = \exp \left( \int_q^{\infty} \langle Z, \hspace{0.17em} \mathrm{d} W \rangle + \frac{1}{2} \int_q^{\infty} \|Z\|_2^2 \right) = \exp \left( A_q - \int_q^{\infty} e_s (Y_s) \hspace{0.17em} \mathrm{d} s \right)\), a functional of the path of \(x\). So the law of \(x\) under \(\mathbb{Q}\) is \(\mathrm{e}^{A_q} \mathrm{e}^{- \int e} \mathbb{R}^{q, x}\), and normalisation gives \(A_q = A (q, x)\). By Theorem 18.4 this is the limit of \(\mathbb{P}^{q, x_N}\). For \(Z\): under \(\mathbb{Q}'\), for the filtration \(\mathcal{F}\), \(W'\) is a Brownian motion and \(x\) is Markov with respect to \(\mathcal{F}\), so the density process on \(\mathcal{F}_t\) is \(D_t =\mathbb{E}' \left[ \mathrm{e}^{A_q - \int_q^{\infty} e} |\mathcal{F}_t \right]\), an adapted functional of the path of \(x\). The drift \(Z\) under \(\mathbb{Q}\) is determined by the covariation of \(\log D\) with \(W'\), which is computed from the path of \(x\) only, since \(C_s \hspace{0.17em} \mathrm{d} W'\) is a differential of \(x\) and its drift.\(\Box\)
So if the backward equation is written for the scalar value \(A\), the solution is unique in law. Its \(Z\) is the feedback \(m_s (x_s) - y_s (x_s)\), and by Theorem 18.6 it coincides with \(\psi - Y\) of (18.16); differentiability of \(A\) in \(x\) is not claimed.
Theorem
where, for \(\mathbb{Q}\) of finite entropy, \(u\) is the drift of \(W\) under \(\mathbb{Q}\) added to (18.4) as \(C_s u_s \hspace{0.17em} \mathrm{d} s\), so that \(Y\) solves \(\hspace{0.17em} \mathrm{d} Y = (b (Y) + H (Y) u) \hspace{0.17em} \mathrm{d} s + H (Y) \hspace{0.17em} \mathrm{d} W^{\mathbb{Q}}\) and \(\text{Ent} (\mathbb{Q}|\mathbb{R}^{q, x}) = \frac{1}{2} \mathbb{E}^{\mathbb{Q}} \int \|u\|_2^2\). For \(O = 0\) the unique minimiser is \(u = Z\), and the value is \(A (q, x)\). In particular, at \((q, x) = (q_0, 0)\), for \(O\) a bounded continuous cylinder function of the terminal field,
the infimum being over the laws of finite entropy with respect to \(\mathbb{R}\), and \(\mathcal{G} (0) = A (q_0, 0)\) is the renormalised free energy (18.14). The minimiser for \(O = 0\) is \(u = Z\). No infinite constant occurs in \(\mathcal{G}\), and there is no initial law to optimise over.
Proof. The Gibbs variational principle: for a probability \(\mathbb{R}\) and a measurable \(\mathcal{S}\) with \(\mathbb{E}^{\mathbb{R}} \mathrm{e}^{-\mathcal{S}} < \infty\), for every \(\mathbb{Q}\) with \(\text{Ent} (\mathbb{Q}|\mathbb{R}) < \infty\), \(\mathbb{E}^{\mathbb{Q}} \mathcal{S}^- \leqslant \text{Ent} (\mathbb{Q}|\mathbb{R}) + \log \mathbb{E}^{\mathbb{R}} \mathrm{e}^{\mathcal{S}^-}\); where \(\mathrm{e}^{\mathcal{S}^-} \leqslant 1 + \mathrm{e}^{-\mathcal{S}}\). This gives that \(\mathbb{E}^{\mathbb{Q}} \mathcal{S}\) is well-defined in \((- \infty, \infty]\) and \(\mathbb{E}^{\mathbb{Q}} \mathcal{S}+ \text{Ent} (\mathbb{Q}|\mathbb{R}) \geqslant - \log \mathbb{E}^{\mathbb{R}} \mathrm{e}^{-\mathcal{S}}\), with equality exactly at \(\hspace{0.17em} \mathrm{d} \mathbb{Q} \propto \mathrm{e}^{-\mathcal{S}} \hspace{0.17em} \mathrm{d} \mathbb{R}\) if \(\mathbb{E}^{\mathbb{Q}} |\mathcal{S}| < \infty\) there. Apply this with \(\mathcal{S}= O + \int_q^{\infty} e\). The integrability \(\mathbb{E}^{\mathbb{R}} \mathrm{e}^{-\mathcal{S}} < \infty\) is Theorem 18.4. At the minimiser for \(O = 0\), \(\mathbb{E} |\mathcal{S}| < \infty\) passes to the limit from (18.11) by Fatou; for \(O\) bounded the same holds as the tilted law has a bounded density with respect to it. Since \(\mathbb{R}^{q, x}\) is the strong solution driven by \(W\), every \(\mathbb{Q}\) of finite entropy has a drift \(u\) with \(\text{Ent} = \frac{1}{2} \mathbb{E}^{\mathbb{Q}} \int \|u\|^2\) by Föllmer's theorem. At \(O = 0\), the minimiser has control \(Z\), by Theorem 18.11 (\(u = Z\) is the Föllmer drift of \(\mathbb{P}^{q, x}\)). The equation for \(Y\) holds under \(\mathbb{R}^{q, x}\) by the proof of Theorem 18.6, hence under \(\mathbb{Q} \ll \mathbb{R}^{q, x}\) with \(\hspace{0.17em} \mathrm{d} W = \hspace{0.17em} \mathrm{d} W^{\mathbb{Q}} + u \hspace{0.17em} \mathrm{d} s\). (18.27) is (18.26) at \((q_0, 0)\), with (18.13).\(\Box\)
Remark
Remark
Remark
The vector FBSDE and strong solutions. Theorem 18.11 gives uniqueness in law for the scalar form. A solution of (18.16) alone need not have \(Z\) of gradient form. It would suffice that any solution has a Lipschitz decoupling field, which needs a pointwise bound on \(\text{Cov}_q (x)\), or high-scale contraction with non-degeneracy on compact intervals; only \(L^2 (\text{HS})\) control of \(\text{Cov}\) is available. The same bound is what is missing for the Polchinski process to be adapted to the innovation \(W\): the explicit flow is a strong solution, the exact one is not known to be. The Allinger–Mitter theorem does not apply: its finite-energy hypothesis is on the signal \(\Phi\), and \(\| \Phi \|_2 = \infty\) here.
Quartic tails at the free threshold. Theorem 17.4 gives quartic moments in \(H^{- \rho}\) for \(\rho > \frac{3}{2}\), and Theorem 17.5 Gaussian moments for \(s > \frac{1}{2}\). The quartic moment at \(s\) near \(\frac{1}{2}\) would need spatially resolved sources.
Axioms. Reflection positivity holds at every lattice, for reflections in lattice and mid-lattice planes (nearest-neighbour action), and passes to \(\nu\) for every reflection in a coordinate plane, by approximating the plane with lattice planes (standard; Exercise 18.4). Rotation invariance (absent on the torus) and clustering need infinite volume.
Infinite volume. The force, its Burgers flow, and differences of free energies are intensive (Section 9.5 of Lecture 5). The estimates of this lecture must then be made local, with weights in space and constants per unit volume. A new difficulty appears in the backward equation: its integrand \(\Xi\) is a nonlocal operator, and the backward error at a point can receive noise from arbitrarily far away. Uniform-in-volume coefficient bounds and local energy moments are themselves open; they could give an infinite-volume Gibbs subsequence. Controlling the “noise from infinity” (together with local compactness of the blocks of the derivative of the force) is the main additional step needed to retain the full FBSDE without an orthogonal martingale.
Exercise
Exercise
Exercise
Exercise
Exercise
Exercise
Exercise
Exercise
Exercise
N. Barashkov, M. Gubinelli. A variational method for \(\Phi^4_3\). Duke Math. J. 169 (2020), 3339–3415.
M. Gubinelli, M. Hofmanová. A PDE construction of the Euclidean \(\Phi^4_3\) quantum field theory. Comm. Math. Phys. 384 (2021), 1–75.
M. Gubinelli, S.-J. Meyer. The FBSDE approach to sine–Gordon up to \(6 \pi\). Preprint, arXiv:2401.13648, 2024.
M. Hairer, J. Mattingly. The strong Feller property for singular stochastic PDEs. Ann. Inst. H. Poincaré Probab. Statist. 54 (2018), 1314–1340.
M. Hairer, K. Matetski. Discretisations of rough stochastic PDEs. Ann. Probab. 46 (2018), 1651–1709.
M. Hairer, P. Schönbauer. The support of singular stochastic partial differential equations. Forum Math. Pi 10 (2022), e1.
M. Hairer, R. Steele. The \(\Phi^4_3\) measure has sub-Gaussian tails. J. Stat. Phys. 186 (2022), art. 38.
J.-C. Mourrat, H. Weber. The dynamic \(\Phi^4_3\) model comes down from infinity. Comm. Math. Phys. 356 (2017), 673–753.
A. Moinat, H. Weber. Space-time localisation for the dynamic \(\Phi^4_3\) model. Comm. Pure Appl. Math. 73 (2020), 2519–2555.
J. Ma, J. Yong. Forward-Backward Stochastic Differential Equations and their Applications. Lecture Notes in Math. 1702, Springer, 1999.